GLOBAL PRESENCE · DUBAI

Clarity for wealth
that moves across borders.

Hexagone Group brings investment oversight, planning structures, insurance solutions and property advisory into one disciplined view — with clear reasoning, precise coordination and a long-term perspective.

A clearer way to manage complexity

Significant wealth rarely sits in one account, one asset class, or one country.

It may involve several banks, currencies, policies, properties, ownership structures, and professional advisers. Without a clear framework, individual decisions can become disconnected from the wider plan.

Hexagone Group provides an organised advisory process. We help clients understand the role of each decision, compare available options, coordinate appropriate specialists, and maintain a clear record as circumstances evolve.

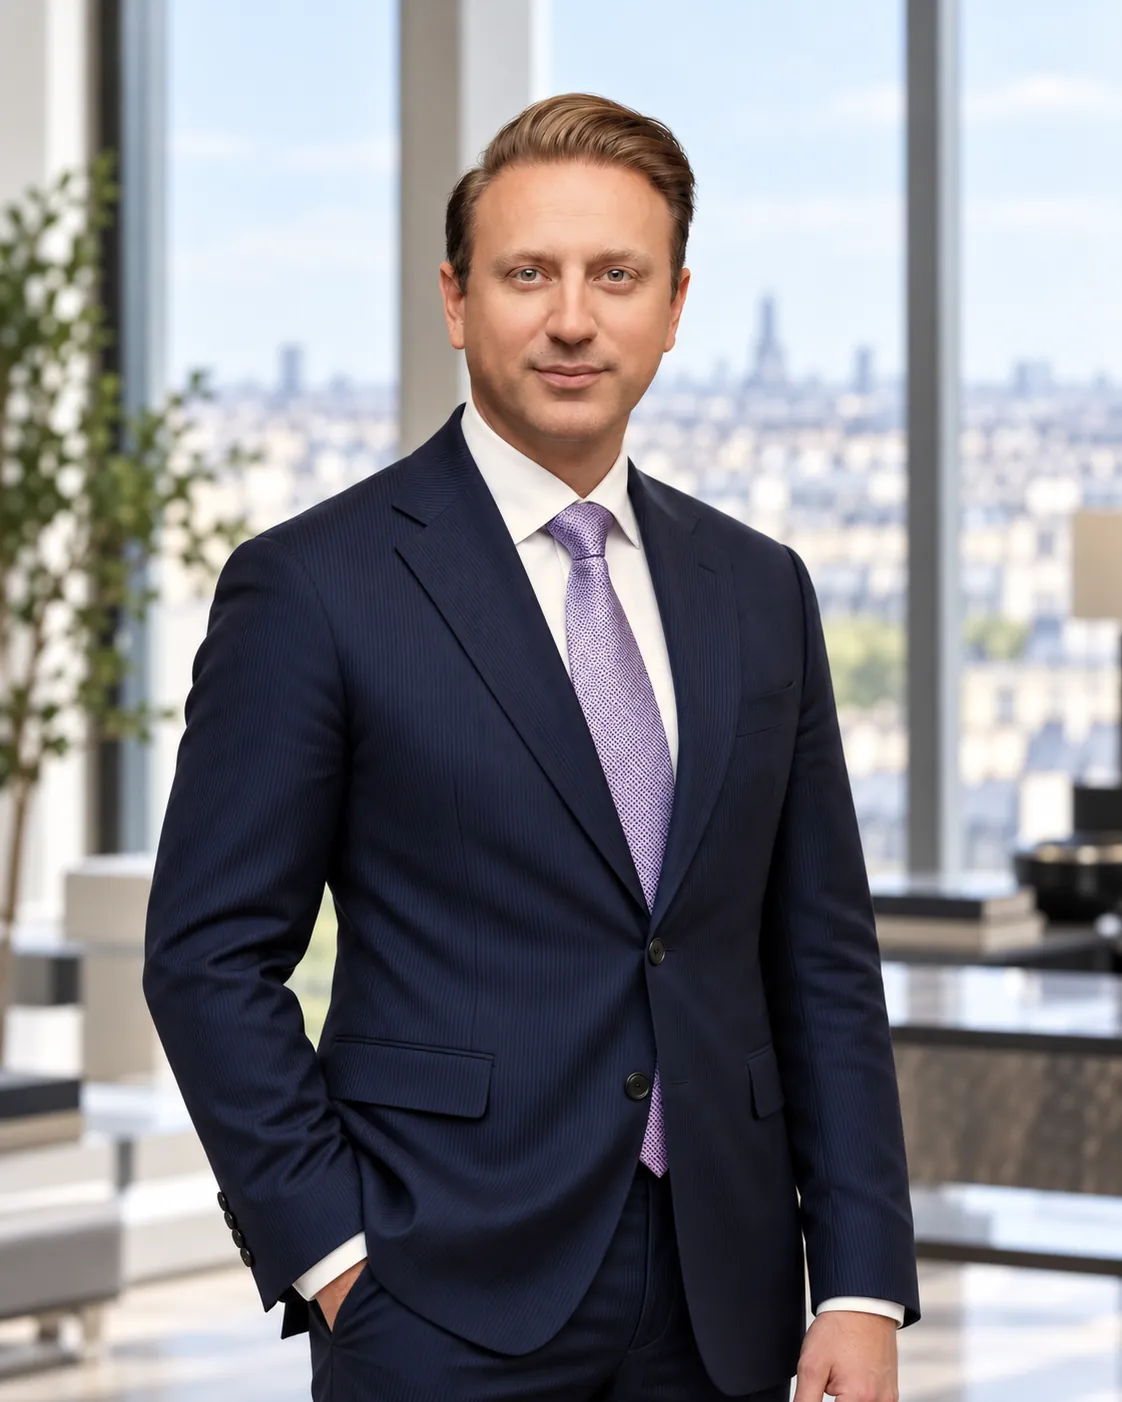
Antoine Bagni, Managing Partner of Hexagone Group
A NOTE FROM OUR MANAGING PARTNER

The whole picture matters.

Welcome to Hexagone Group.

International wealth rarely stands still. It evolves across markets, institutions, family priorities and places. Our role is to understand how those pieces connect, bring structure to the decisions that matter, and keep the long term clearly in view.

For us, good advice is not only about what happens today, but about maintaining clarity and continuity as circumstances change. That perspective is captured in a simple idea at the heart of Hexagone: Your Future, Our Mission.

Antoine Bagni
Managing Partner
The standard behind every decision

Clarity first.
Structure second.

Four principles guide how advice is framed, documented, and reviewed over time.

01

Clarity

Every recommendation should have a clear purpose, place, and consequence within the wider plan.

02

Independence

Options are assessed for suitability, quality, transparency, access, and long term fit.

03

Discipline

Decisions are documented, monitored, and reviewed against defined objectives and constraints.

04

Continuity

The advisory structure should remain useful as markets, locations, and priorities change.

One advisory process

From first review to ongoing oversight.

A disciplined process keeps the wider picture visible while decisions move from definition to implementation and review.

01

Understand the full picture.

We begin with the client balance sheet, objectives, constraints, relationships, and future plans.

02

Define priorities and decision rules.

We identify what matters most and establish a clear basis for comparing options.

03

Coordinate suitable providers.

Banks, insurers, legal advisers, lenders, and other professionals are involved where required.

04

Review progress and adapt.

Decisions, documents, risks, and next steps remain visible as circumstances change.

Perspective for better decisions

Research designed to make complex subjects easier to assess.

Research and practical guidance on investment structures, planning, insurance, and international property.

View Insights→
Frequently asked

A clear starting point.

What does Hexagone Group do?

Hexagone Group provides wealth advisory and professional coordination across investment advisory, insurance planning, alternative investments, wealth planning, and global property. The exact scope depends on the relevant entity, jurisdiction, client circumstances, and provider requirements.

Who does Hexagone Group work with?

We work with international clients whose assets, banking relationships, business interests, or future plans require a coordinated and disciplined advisory view.

How does the advisory process begin?

The process begins with a structured review of objectives, assets, liabilities, liquidity needs, jurisdictions, existing relationships, and future priorities. This creates the basis for clear decisions and suitable specialist input.

Does Hexagone Group provide every specialist service directly?

No. Hexagone Group acts in an advisory and coordination capacity. Independent licensed partners or client appointed advisers are involved where specialist, regulated, legal, insurance, lending, residency, citizenship, or real estate services are required.

How are decisions reviewed over time?

The relevant structure, allocation, provider relationship, documentation, risk, and next decision points are reviewed through a clear ongoing record.

About Hexagone Group

A firm built around clarity, accountability, and long term trust.

Hexagone Group was created to give international clients a more personal and disciplined standard of wealth advisory. Our work combines close attention with clear process, documented decisions, and access to appropriate specialists across markets.

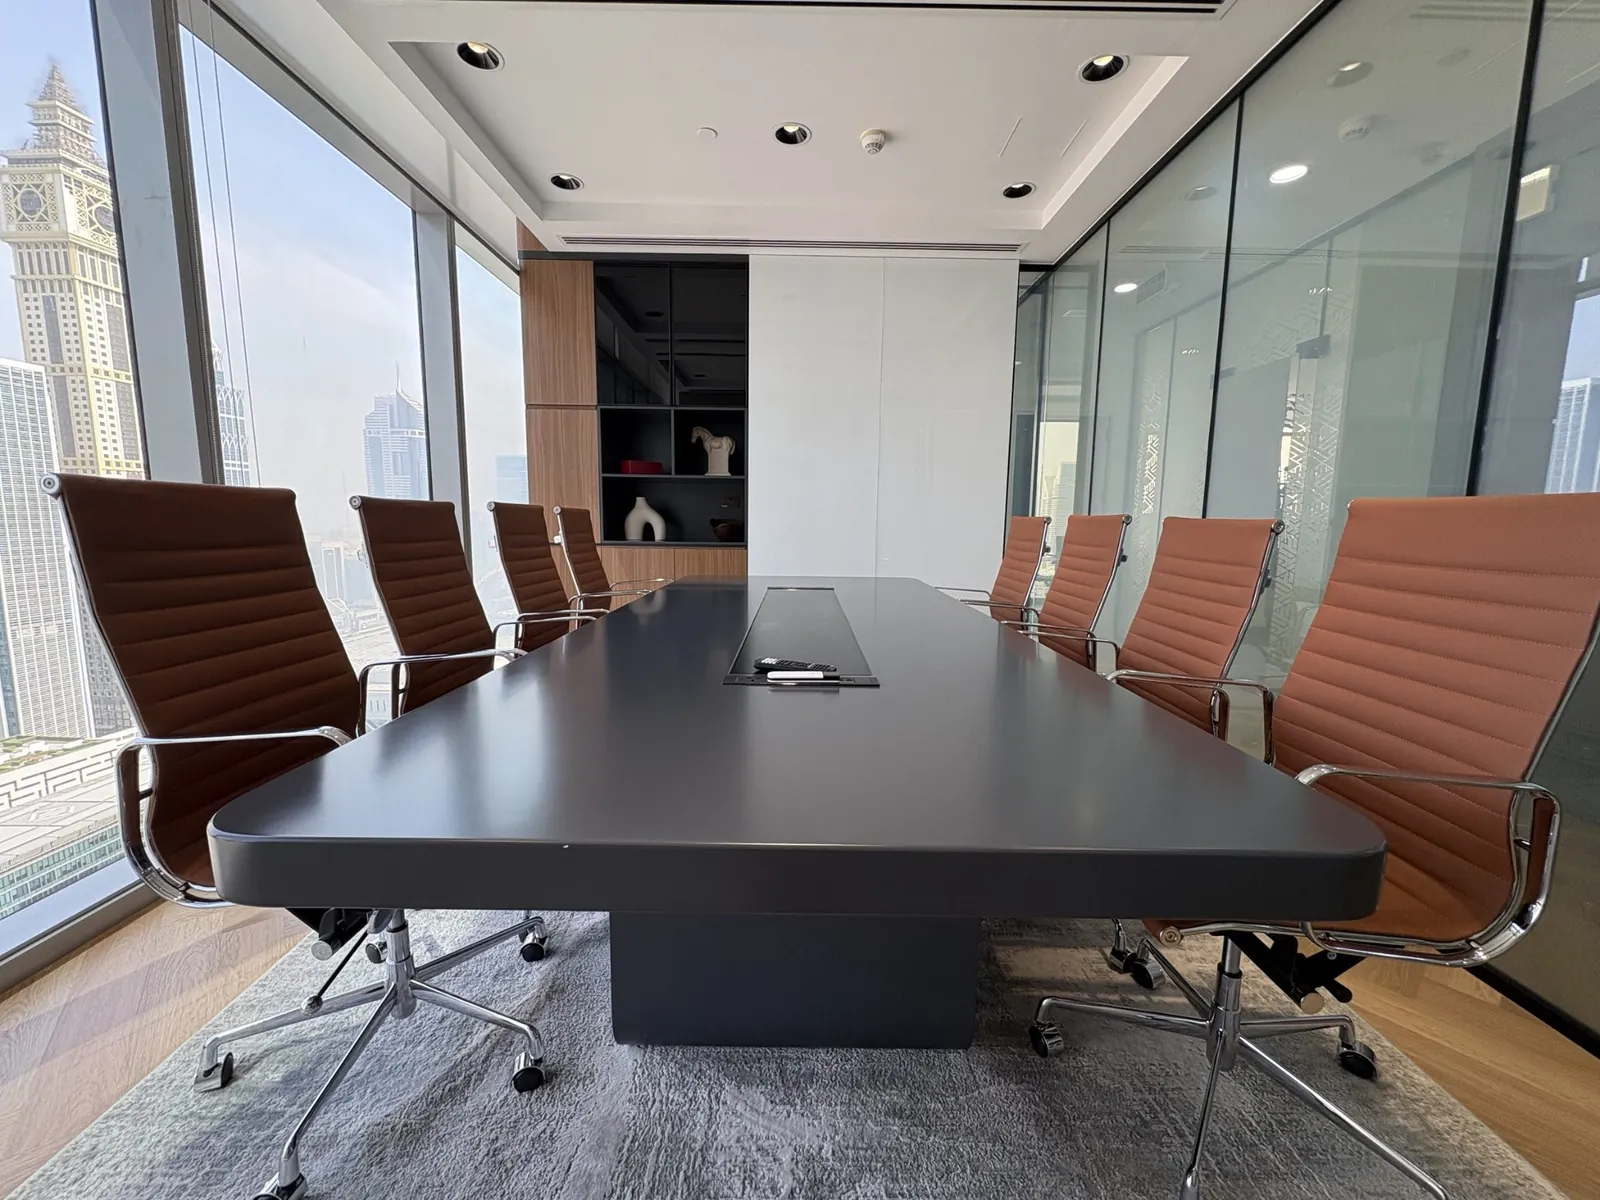
Hexagone Capital Dubai office boardroom overlooking the DIFC skylineHEXAGONE GROUP DUBAI
Our story

Boutique attention. International perspective.

Hexagone Group began with a shared belief from founders Antoine Bagni and David Palacci: clients with international lives needed advice that combined the attention of a boutique firm with the discipline expected from established financial institutions.

As Damien Soler, Dennis Ceragioli, and Oscar Lacroix joined the partnership, the firm expanded its expertise and international reach while retaining the same principle: understand the whole situation before recommending any individual action.

The name Hexagone reflects the firm French roots and the idea of a complete perspective. Today, the Group supports clients through affiliated companies and professional relationships across Europe, the Middle East, and Asia.

Our Mission

To bring clarity and coordination to significant financial decisions.

Helping clients understand not only what they own, but why each structure belongs in the wider plan.

Our Aspiration

To be recognised for disciplined international advice.

Precise coordination with partners and a standard of service that remains personal at every stage.

Our principles

The standards that shape the work.

Client Focus

The work begins with the client situation, objectives, constraints, and priorities.

Independence

Options are assessed on their merits, transparency, suitability, and long term fit.

Accountability

Responsibilities, decisions, and next steps should be clear at every stage.

Excellence

High standards are applied to research, documentation, provider selection, and service.

Adaptability

The advisory framework should remain useful as markets, jurisdictions, and circumstances change.

Service

Responsiveness, discretion, and continuity are central to the client relationship.

Leadership

Experience, judgement, and international perspective.

Hexagone Group is led by a partnership with experience across international wealth advisory, client relationships, and business development.

Antoine BagniManaging Partner
David PalacciSenior Partner
Damien SolerPartner and Head of Human Division
Oscar LacroixPartner
Dennis CeragioliPartner and Dubai Area Manager
Hexagone Group leadership team
Group entities

Hexagone Group companies and international presences.

Explore the five Hexagone companies and presences presented on this website. Regulatory details are stated only where verified and applicable to the relevant entity.

01 · Group entity

Hexagone Capital Dubai

Dubai, United Arab Emirates

DFSA-regulated entity
View entity
02 · Group subsidiary

Hexagone Group Bali

Bali, Indonesia

Hexagone Group subsidiary
View entity
03 · Group subsidiary

Hexagone Group Malaysia

Malaysia

Hexagone Group subsidiary
View entity
04 · Group subsidiary

Hexagone Shanghai

Shanghai, China

Hexagone Group subsidiary
View entity
05 · Group entity

Hexcap France

Paris, France

ANACOFI-CIF / ORIAS registered
View entity
Hexagone Capital Dubai

Hexagone Capital (UAE) Limited

Dubai, United Arab Emirates

Entity information

Hexagone Capital Dubai

Hexagone Capital (UAE) Limited is regulated by the Dubai Financial Services Authority (DFSA), Firm Reference Number F007596.

EntityHexagone Capital (UAE) Limited
JurisdictionDubai, United Arab Emirates
Regulatory StatusRegulated by the Dubai Financial Services Authority (DFSA)
Authorised Activities

Authorised Activities

Advising on Financial Products
Arranging Custody
Arranging Deals in Investments
Insurance Intermediation
Client Support

Complaint Handling

Complaints concerning Hexagone Capital (UAE) Limited are handled under the entity's applicable complaint-handling procedure.

VIEW DUBAI COMPLAINT HANDLING PROCEDURE →
Hexagone Group Dubai team portrait in the Dubai office with the skyline visible behind them
Dubai

The team in Dubai

Our Dubai team brings together local market knowledge and international wealth-management experience, supporting clients from our base in the Dubai International Financial Centre.

EntityHexagone Capital Dubai
Dubai enquiries

Start a conversation with Hexagone Group.

Use the central enquiry form to share your location and the nature of your enquiry.

Start a Dubai enquiry→
Entity disclosure

Services and regulatory scope depend on the relevant legal entity, jurisdiction, client circumstances, and provider requirements.

Hexcap France

Hex Cap (France)

Paris, France

Entity information

Hexcap France

Hex Cap (France) is registered with ANACOFI-CIF — National Association of Financial Advisers — under registration number E009790. ANACOFI-CIF is an association approved by the Financial Markets Authority. Hex Cap (France) is also registered as Insurance and re-insurance brokers, Category B, with the Organization for the Registration of Assurance Intermediaries (ORIAS), registration number 21007618.

Legal company nameHex Cap (France)
Address162 boulevard Pereire
75017 Paris, France
ANACOFI-CIF RegistrationE009790
Scope of activity

Scope of activity

Conseil en investissements financiers
(conseil sur instruments financiers, sur la fourniture de services d'investissement, sur des opérations sur biens divers)
Réception-transmission d'ordres à titre accessoire

ORIAS: www.orias.fr

EntityHexcap France
France enquiries

Start a conversation with Hexagone Group.

Use the central enquiry form to share your location and the nature of your enquiry.

Start a France enquiry→
Entity disclosure

Services and regulatory scope depend on the relevant legal entity, jurisdiction, client circumstances, and provider requirements.

Shanghai, China

Hexagone Shanghai

Hexagone Group subsidiary in Shanghai, China.

Group subsidiary

Hexagone Shanghai

Hexagone Shanghai is presented on this website as a Hexagone Group subsidiary in Shanghai.

LocationShanghai, China
PresentationHexagone Group subsidiary
AddressLevel 7, Eco City, 1788 Nanjing West Road, Shanghai, China
Local Leadership

Oscar Lacroix

Partner

Supporting Hexagone Group's presence and international relationships in Shanghai.

Start a conversation
Oscar Lacroix, Partner at Hexagone Group
Shanghai

The team in Shanghai

Our Shanghai team combines local perspective with the wider capabilities of Hexagone Group, supporting internationally minded clients from our presence in one of Asia's leading financial centres.

Hexagone Group Shanghai team in their Shanghai office
SubsidiaryHexagone Shanghai
Shanghai enquiries

Start a conversation with Hexagone Group.

Use the central enquiry form to share your location and the nature of your enquiry.

Start a Shanghai enquiry→
Other International Market

Other International Market

Multiple jurisdictions

Entity information

Other International Market

For markets not covered by a named regional destination, the central enquiry route helps identify the appropriate Hexagone contact for the jurisdiction and request.

Legal nameOther International Market
JurisdictionMultiple jurisdictions
Contact addressContact through the central enquiry form and select Other International Market.
Entity routeInternational / Other
Other International Market

Use the regional Hexagone enquiry route.

The central enquiry form identifies your location, principal need, and the relevant legal entity before your request is directed onward.

Start an international enquiry→
Entity disclosure

Services and regulatory scope depend on the relevant legal entity, jurisdiction, client circumstances, and provider requirements.

Services

A coordinated view
of wealth.

Our advisory work is organised around the decisions that shape international wealth. Five connected areas, each with a clear purpose and a disciplined process.

Explore the five areas ↓
How services connect

One decision often affects another.

An investment account can influence currency management. A policy structure can affect liquidity and beneficiary planning. A property decision can change financing needs and portfolio concentration.

The advisory process considers each service in the context of the wider plan.

Start with the wider picture

Bring the next decisions into one clear advisory view.

Start a Conversation→
Tailored advisory

Investment Advisory

Independent portfolio advisory for international clients who want clarity, discipline, and a structure that can be explained at every level.

The advisory view

Investment decisions should not feel like isolated reactions to markets. They should sit inside a written investment policy, with defined objectives, liquidity ranges, currency preferences, and a clear view of how each holding contributes to the whole.

Hexagone Group advises clients whose lives, assets, and banking relationships often span more than one country. The review begins with the balance sheet and extends to account structure, allocation, manager selection, reporting, and portfolio oversight.

Our advisory work is open, selective, and guided by suitability. Funds, instruments, discretionary mandates, banking access, and account providers are assessed on merit, transparency, and long term fit.

01

Designed For Clients Who Want

  • A consolidated investment view across banks, account providers, and currencies.
  • A written investment policy that defines risk, liquidity, exclusions, and review rules.
  • Independent assessment of funds, managers, instruments, and mandates.
  • Clearer visibility on currency exposure, liquidity, reporting, and portfolio role.
  • A structured review process supported by concise records and reasoned decisions.
02

The Advisory Method

01

Profile: Objectives, balance sheet, liquidity needs, time horizon, base currency, and reporting requirements are mapped.

02

Policy: The investment policy, allocation ranges, constraints, and review rules are defined in writing.

03

Portfolio structure: Banking access, cash management, core exposure, and specialist allocations are reviewed together.

04

Implementation review: Instruments, managers, share classes, platform fit, and path to allocation are assessed before action is taken.

05

Ongoing review: Performance, attribution, risk, liquidity, currency exposure, and next decisions are reviewed through a documented record.

Client understanding

What turns client circumstances into portfolio decisions?

The advisory work links the client’s practical constraints to decisions about allocation, implementation and ongoing review.

ObjectivesWhat the capital is expected to support.
Time horizonWhen capital may be needed.
LiquidityCash needs and access requirements.
Base currencyThe currency used to assess the portfolio.
Existing assetsWhat is already held and where.
Risk parametersLimits that guide portfolio construction.
Portfolio decisions

One set of circumstances, several investment decisions

  • Strategic asset allocation
  • Cash allocation
  • Currency exposure
  • Manager and instrument selection
  • Custody and implementation
  • Monitoring and reporting
03

What Remains Under Review

  • Strategic allocation and actual weights.
  • Portfolio volatility, drawdown profile, and concentration.
  • Currency exposure against the client base currency.
  • Cash needs, redemption windows, and funding events.
  • Manager discipline, mandate consistency, and reporting clarity.
05

Enduring Value

A well governed portfolio should give the client more than performance figures. It should give context, control, and confidence that decisions are being made inside a clear investment discipline.

Service Enquiry

Discuss how your investment objectives, existing arrangements, liquidity, currency exposure and reporting can be reviewed within a structured advisory process.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Investment Advisory

International Investment Account

A global account review designed to keep wealth visible, organised, and aligned with the way the client lives across borders.

The advisory view

For clients whose assets, residence, or family interests extend across more than one country, the account setup matters as much as the allocation itself. Currency, access rights, reporting, and transfer rules all influence how efficiently wealth can be reviewed over time.

Hexagone Group provides advisory review on international investment account options with banking partners and account providers where suitable. The aim is clarity in ownership, permissions, reporting, liquidity, and currency policy.

01

Where It Adds Value

  • The client holds assets in more than one jurisdiction.
  • The client wants a clearer global investment account with consolidated reporting.
  • The client needs currency control for income, spending, or future liabilities.
  • The client wants access rights, investment permissions, and reporting organised in one place.
02

Account Review Path

01

Provider fit: Account providers are compared by jurisdiction, service standard, market access, reporting, and currency capability.

02

Opening record: Required documents, declarations, and supporting evidence are reviewed according to provider requirements.

03

Transfer plan: Existing assets, expected timing, restrictions, and cash requirements are mapped.

04

First allocation review: The opening portfolio structure, currency policy, and reporting baseline are established.

03

Planning Decisions

  • Base currency and working cash policy.
  • Eligible markets and instrument access.
  • Account ownership and authorised signatories.
  • Reporting frequency and statement format.
  • Rebalancing rules and liquidity reserves.
04

Operating Clarity

The right account setup gives wealth a reliable operating base. It improves visibility and creates a cleaner foundation for investment decisions.

Portrait of Victor Baffet
Victor BaffetVice President, Wealth Management
Advisor Perspective

Victor Baffet on international investment accounts

Global marketsCurrenciesJurisdiction choice

An International Investment Account gives clients access to a broad range of asset classes across global markets and currencies. This includes equities, bonds, ETFs, mutual funds, commodities, cryptocurrencies and structured products. Key considerations include the client’s objectives, timeframe, risk profile, currency exposure and choice of jurisdiction.

Service Enquiry

Review account structure, provider options, reporting format and currency policy within the context of your international arrangements.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Investment Advisory

Private Banking Relationships

Private banking access reviewed through thorough selection, relationship terms, and ongoing oversight.

The advisory view

A private bank should serve the client plan rather than define it. The right relationship can provide banking access, secured lending, investment access, foreign exchange, reporting, and specialist support. The wrong one can add unnecessary complexity.

Hexagone Group provides advisory review across booking centres and private banking institutions. The focus is suitability, balance sheet strength, service standard, lending terms, and the quality of the operating model.

01

When the Relationship Matters

  • The client is opening a new private banking relationship.
  • The client wants to compare banks before transferring assets.
  • The client needs credit, secured lending, investment access, or specialist banking support.
  • The client already has multiple relationships and wants clearer service discipline.
02

Relationship Review Path

01

Bank mapping: Institutions are assessed by balance sheet, booking centre, product access, service quality, and cultural fit.

02

Introduction brief: A clear client summary is prepared so the bank understands expected assets, needs, and decision criteria.

03

Relationship terms: Lending conditions, collateral rules, foreign exchange access, reporting, and service commitments are compared.

04

Operating model: Named contacts, instruction rules, reporting format, and escalation points are defined.

05

Review record: Service quality, facility terms, and continued relevance are reassessed over time.

03

Banking Review Areas

  • Booking centre and account setup.
  • Credit line terms, collateral rules, and margin call process.
  • Minimum relationship size and platform access.
  • Service level commitments and access to specialists.
  • Instruction rules, reporting quality, and response standards.
04

Relationship Quality

Good private banking is not only about access. It is about responsiveness, governance, service depth, and whether the relationship continues to earn its place inside the client plan.

Lucas Dragon

Lucas Dragon

Dubai Area Manager

Advisor View

Selecting the right private banking relationship

A private banking relationship should go beyond access to investment products. The right banking partner should provide the appropriate combination of service, custody, investment access, financing capabilities and reporting for the client’s circumstances.

ServiceCustodyInvestment accessFinancingReporting

“From an advisory perspective, the key is to assess the institution, jurisdiction, platform capabilities and overall fit within the client’s broader wealth strategy.”

Service Enquiry

Compare private banking relationships, service models, lending considerations and the operating standards that matter to your wider plan.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Investment Advisory

Discretionary Fund Management

Access to external independent Discretionary Fund Managers, with manager selection, comparison and ongoing oversight.

Hexagone Group does not provide discretionary fund management services directly. We provide access to external, independent Discretionary Fund Managers and support clients in their selection, comparison and ongoing review. Any appointment or replacement of an external manager is subject to the client’s authorisation and applicable agreements.

The advisory view

Discretionary Fund Management can provide clients with access to professional portfolio management through external, independent investment managers.

Through our independent advisory approach, we help clients assess suitable managers, compare their investment capabilities, service standards and fee structures, and review appointed relationships over time.

01

Why Clients Use External Managers

  • Access professional day-to-day portfolio management through an external independent Discretionary Fund Manager.
  • Compare and challenge different external managers across investment approach, capabilities, service quality and fee structures.
  • Select an external manager whose mandate and risk-return approach align with the client’s objectives and requirements.
  • Maintain independent review and oversight of the appointed manager and consider replacement where appropriate, subject to the client’s authorisation and applicable agreements.
02

External Manager Review Path

01

Define objectives

Understand the client’s investment objectives, requirements, risk profile, liquidity needs and wider portfolio context.

02

Review and compare managers

Assess suitable external Discretionary Fund Managers and compare their investment approach, capabilities, service quality and fee structures.

03

Support selection and appointment

Support the client in selecting and appointing an external manager for part or all of the portfolio, or replacing an existing manager, subject to the client’s authorisation and applicable agreements.

04

Review over time

Monitor the appointed external manager and review whether the strategy, service and relationship remain aligned with the client’s objectives.

External manager mandate

Where does discretionary authority sit?

Any day-to-day discretionary investment decisions are made by the appointed external independent Discretionary Fund Manager within the mandate agreed with the client. Hexagone Group does not exercise that discretion.

ObjectivesThe client’s purpose and return objectives as documented in the external manager mandate.
Risk limitsConstraints that define the permitted range of decisions for the external manager.
LiquidityAccess needs and permitted liquidity profile agreed with the external manager.
Permitted investmentsThe investments the external manager may and may not use under the mandate.
External manager discretion

The appointed external manager may make portfolio decisions only within the client-approved mandate. Hexagone Group’s role is advisory, focused on access, selection, comparison and ongoing oversight.

  • Security selection
  • Position sizing
  • Rebalancing
  • Cash management
  • Implementation timing
  • Mandate execution
03

Manager Oversight

  • Performance and risk in the context of the external manager’s stated mandate and objective.
  • Investment approach, implementation discipline and consistency of positioning.
  • Liquidity, concentration, currency exposure and other mandate-relevant risks.
  • Reporting quality, service standards and responsiveness to client requirements.
  • Fee structure and whether the external manager relationship remains appropriate over time.
04

Independent Oversight

Hexagone Group provides access to, selection of, comparison and ongoing oversight of external independent Discretionary Fund Managers. We do not manage client portfolios on a discretionary basis. Where circumstances change, we can compare alternative managers and support the replacement of an external manager for part or all of the portfolio, subject to the client’s authorisation and applicable agreements.

Service Enquiry

Review external Discretionary Fund Managers, compare their investment approach, service quality and fee structures, and assess which manager may be appropriate for your objectives.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity and does not provide discretionary fund management or exercise discretionary investment authority over client assets. Discretionary portfolio management is carried out by external independent managers appointed by the client under separate applicable agreements.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Investment Advisory

Mutual Funds and ETFs

Liquid investment building blocks selected for purpose, quality, liquidity, and clarity.

The advisory view

Mutual funds and ETFs can form the core of a disciplined portfolio when each holding has a clear role. The question is not only which market to access, but how to access it with the right structure, currency exposure, and liquidity profile.

Hexagone Group reviews fund and ETF exposure through an open selection process. The review considers manager quality, index methodology, liquidity, tracking discipline, distribution policy, and platform compatibility.

01

Portfolio Role

  • The client wants efficient access to equities, bonds, cash, or specialist market segments.
  • The client wants a cleaner fund list with fewer overlaps.
  • The client wants stronger discipline across fund selection and portfolio role.
  • The client wants rules for rebalancing, income treatment, and currency exposure.
02

Review Method

01

Portfolio role: Each fund or ETF is assigned a purpose inside the allocation.

02

Instrument review: Liquidity, track record, methodology, holdings, currency, and platform fit are assessed.

03

Implementation rule: Entry points, ticket size, rebalancing range, and exit criteria are documented.

Comparison

Mutual fund and ETF: what changes for the investor?

Both can provide access to pooled portfolios. The main practical differences are how investors trade and how the purchase or sale price is determined.

Mutual fund
ETF
Portfolio
Pooled portfolio managed under the fund’s stated objective.
Investor dealing
Shares are bought from or redeemed with the fund.
Retail investors generally buy and sell shares on an exchange through a brokerage account.
Pricing
Transactions occur at the next calculated net asset value, subject to applicable fees.
Trades occur at market prices during the trading day, which can be above or below NAV.
Management style
Active and index approaches are available.

The characteristics of a specific fund depend on its prospectus, portfolio, fees, dealing terms and market conditions.

03

Core Components

  • Global equity exposure for long term growth.
  • Investment grade bonds for income and portfolio stability.
  • Money market and short duration funds for liquidity reserves.
  • Hedged share classes where currency risk should be reduced.
  • Selective satellites for themes, factors, or regional exposure where the case is strong.
04

Selection With Restraint

Fund selection is strongest when restraint comes first. A smaller, cleaner list of well chosen holdings often gives the portfolio more discipline than a large collection of ideas.

Service Enquiry

Review fund selection, currency exposure, costs and the role each holding may play within your broader portfolio.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Tailored advisory

Private Placement Life Insurance

A refined policy structure designed for long term planning, investment access, cross border continuity, and governance.

The advisory view

Private Placement Life Insurance brings investment management and life insurance into one precisely specified policy structure. For clients with cross border planning needs, it can support planning across residence, succession, reporting, and wealth governance when designed with the right jurisdiction, carrier, ownership language, and investment menu.

Hexagone Group works with appropriate providers and professional advisers to help clients assess whether this type of arrangement is suitable. The advisory review focuses on policy design, jurisdiction fit, carrier quality, premium structure, eligible investments, reporting, and ongoing policy health.

The structure should be precise rather than complex. Every element, from beneficiary provisions to investment rules, must be capable of being understood by the client, legal advisers, carrier, policy administrator, and future advisers.

01

The Role of the Policy

  • A policy structure for long term capital with clear governance.
  • Investment access within a life insurance arrangement where suitable and permitted.
  • Beneficiary language and ownership terms that support planning objectives.
  • Cross border continuity for a life that may involve more than one jurisdiction.
  • Regular review of policy value, allocation, funding assumptions, and policy mechanics.
Policy structure

What does the insurance wrapper sit around?

The policy is the legal insurance contract. The investment arrangements sit within the policy terms rather than being the same thing as the policy itself.

Policyholder

Owns the policy and acts within the contract terms.

Insurance contract and carrier

The policy defines insurance benefits, administration, permitted investments and other contractual terms.

Investment and custody arrangements

Permitted assets, managers and custody arrangements depend on the provider, jurisdiction and policy.

Beneficiary designationBeneficiary provisions form part of the policy and are subject to the contract and applicable law.

Illustrative only. Policy structure, legal treatment, eligible assets and custody arrangements vary by jurisdiction, insurer and contract.

02

Seven Point Design Review

01

Suitability review: Objectives, residence, family needs, liquidity, and reporting obligations are reviewed with professional advisers where required.

02

Jurisdiction assessment: Available policy options are compared for recognition, supervision, administration, and practical use.

03

Carrier selection: Providers are reviewed for financial strength, service quality, investment menu, reporting, and operational reliability.

04

Policy specification: Ownership, beneficiaries, premium pattern, access rights, and signatory rules are documented precisely.

05

Investment menu: Eligible managers, funds, mandates, and cash options are screened for purpose, liquidity, and policy compatibility.

06

Funding plan: Premium timing, currency, liquidity reserves, and conservative assumptions are agreed before activation.

07

Policy review: Values, allocation, funding, beneficiary language, and amendments are reviewed through a formal record.

03

Before Implementation

  • Who owns the policy and who can act on it.
  • How beneficiaries are defined and updated.
  • Which investments are eligible inside the policy.
  • How premiums are funded and in which currency.
  • How statements, valuations, amendments, and policy records will be handled.
05

Clear by Design

A strong policy structure should not depend on complexity. It should depend on suitability, precise documentation, conservative assumptions, and a clear record that can remain useful through time.

Service Enquiry

Review whether a policy structure may support your planning, investment and cross-border objectives over time.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Private Placement Life Insurance

European Life Insurance

A European policy structure designed for administrative clarity, recognised practice, and long term planning.

The advisory view

European life insurance can provide a structured home for capital where the chosen jurisdiction, carrier, and policy language are aligned with the client. The value lies in clarity: clear ownership, clear beneficiaries, clear reporting, and a policy that can be understood by advisers and institutions in the jurisdictions that matter.

Hexagone Group helps clients compare available European policy options and providers with attention to suitability, supervision, investment access, beneficiary provisions, administrative standards, and future residence changes.

01

Why Jurisdiction Choice Matters

  • The client wants a recognised European insurance based planning structure.
  • The client needs beneficiary clarity and professional reporting.
  • The client wants investment access inside a regulated policy structure where suitable.
  • The client values continuity across residence, banking, and family planning needs.
02

Policy Review Path

Current review focus
01

Profile review

Residence, family situation, assets, reporting obligations, and planning objectives are mapped.

03

Long Term Clarity

The strength of a European policy is not only in the jurisdiction selected. It is in how clearly the structure is specified and how consistently it is reviewed.

Dennis Ceragioli, Partner and Dubai Area Manager
Dennis CeragioliPartner and Dubai Area Manager
Partner Perspective

A policy should fit the wider plan

European life insurance solutions can offer international clients a flexible, regulated structure for holding investments and planning succession.

For HNWI who are used to their current platform, a European Life Insurance can also come handy as a pure wrapper. As part of a wider wealth-planning strategy, it should be tailored to your long-term objectives and reviewed regularly.

Key considerations
01Objectives
02Jurisdiction
03Liquidity
04Provider
05Investment options
Service Enquiry

Compare European policy structures, carriers, policy terms and documentation requirements with greater clarity.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Private Placement Life Insurance

Offshore Life Insurance

A cross border policy structure for clients whose personal, professional, or family life extends across borders.

The advisory view

Offshore life insurance can support clients with cross border planning needs when flexibility is combined with exact governance. The policy must be designed to remain understandable as residence, reporting needs, banking relationships, and family circumstances change.

Hexagone Group reviews policy jurisdictions, carriers, premium structure, currency denomination, beneficiary provisions, and eligible investments with attention to long term practicality. The objective is continuity without losing clarity.

01

Designed for Cross Border Needs

  • The client expects future residence changes.
  • The client wants investment and protection features inside a policy structure.
  • The client needs clear beneficiary language that can be understood across borders.
  • The client wants a policy that can support long term planning without repeated restructuring.
02

Cross Border Review

01

Mobility review: Current and likely future jurisdictions are mapped with advisers where required.

02

Jurisdiction fit: Policy centres are compared for standards, recognition, reporting, and provider strength.

03

Policy specification: Ownership, beneficiary provisions, premium design, currency, and access rights are documented.

04

Investment rules: Eligible managers and instruments are defined with attention to liquidity, purpose, and governance.

05

Change management: Future amendments, residence moves, beneficiary updates, and reporting needs are managed through a written record.

03

Continuity With Control

A flexible policy still needs disciplined rules, clear records, and conservative assumptions. Continuity only has value when the documentation remains precise.

Oscar Lacroix, Partner at Hexagone Group

Oscar Lacroix

Partner

Partner Perspective

International structures require careful alignment

Offshore Life Insurance can provide an international framework for holding and managing investment assets within a life insurance structure. When considering this type of solution, factors such as jurisdiction, provider strength, investment flexibility, liquidity, portability and the client’s wider wealth-planning objectives should be carefully reviewed.

International fit
JurisdictionProvider strengthInvestment flexibilityLiquidityPortability
Long-term fit

“The value of an offshore life insurance structure lies in how well it fits the client’s broader circumstances and long-term objectives. Provider selection, jurisdiction, investment flexibility and the structure of the policy should all be considered carefully before proceeding.”

Service Enquiry

Review policy jurisdiction, carrier strength, beneficiary provisions and the practical requirements that support a clear long-term structure.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Private Placement Life Insurance

Index Universal Life Insurance

Permanent protection with index linked crediting rules, prudent funding, and ongoing policy health review.

The advisory view

Index Universal Life Insurance combines permanent life cover with interest crediting linked to approved market indices through defined contract rules. It can support protection and planning objectives when the policy is funded conservatively and reviewed through realistic assumptions.

Before accepting a policy, the client should understand how index options, participation rates, floors, policy loans, crediting assumptions, and surrender values can affect long term outcomes. Illustrations should be read as scenarios rather than promises.

01

Protection First

  • The client wants permanent protection rather than temporary cover.
  • The client wants crediting linked to index rules without direct market ownership inside the policy.
  • The client is prepared to fund the policy with long term discipline.
  • The client wants policy loans and cash value features reviewed with caution and clear limits.
02

Policy Funding Review

01

Protection need

Define cover, optional benefits, beneficiaries and planning purpose.

02

Carrier review

Review financial strength, policy terms, administration and crediting history.

03

Funding blueprint

Test premium timing, reserve margin and lapse tolerance conservatively.

04

Crediting strategy

Compare index options, participation rates, floors and fixed account options.

05

Loan discipline

Set access rules intended to protect policy integrity.

06

Health review

Monitor cash value, crediting, loan balance and lapse margin.

Policy mechanics

How can index-linked crediting affect cash value?

An IUL policy links part of its cash-value crediting method to an external index. That is not the same as directly investing in or owning the index.

PremiumPremiums fund the insurance policy.
ChargesPolicy charges and insurance costs are deducted according to the contract.
Cash valueRemaining policy value is subject to the policy’s crediting rules and other terms.
BenefitThe death benefit is an insurance feature governed by the policy.
Index-linked crediting method

The insurer applies the policy’s stated formula to determine credited interest. The policyholder does not directly own the reference index through this crediting method.

Participation rate, if applicableCap, if applicableFloor or minimum, subject to contractCrediting period

Actual crediting methods, guarantees, charges and policy terms vary. This diagram does not show or imply a future return.

03

Policy Indicators

  • Premium paid compared with planned premium.
  • Net cash value and surrender value.
  • Current participation rate and floor.
  • Loan balance and policy lapse margin.
  • Projected values under conservative crediting assumptions.
04

Funding With Discipline

The quality of an Index Universal Life policy depends on funding discipline and regular review. Protection should remain the anchor, while crediting features are assessed with caution and evidence.

Antoine Bagni, Managing Partner of Hexagone Group
Managing Partner Perspective

Long-term structure matters

Long-term planningLiquidityJurisdictionLegacy

Index Universal Life Insurance should be viewed as a long-term wealth and legacy planning solution rather than simply an insurance product. Its value depends on careful structuring around the client’s objectives, jurisdiction, liquidity needs and risk profile, which is why independent advice is particularly important.

Antoine BagniManaging Partner
Service Enquiry

Assess funding assumptions, crediting rules, policy terms and the long-term resilience of an Index Universal Life arrangement.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Private Placement Life Insurance

Variable Universal Life Insurance

Permanent protection with market linked investment options and rigorous policy governance.

The advisory view

Variable Universal Life Insurance combines permanent life cover with investment allocation inside the policy. The structure can be useful, but it requires precise specification because market returns, cash value, and lapse risk all interact over time.

Hexagone Group helps clients review policy design, ownership, beneficiaries, carrier quality, investment menu, allocation rules, rebalancing, and policy health. The objective is to keep protection and investment exposure in balance.

01

Protection and Market Exposure

  • The client wants permanent protection with market linked growth potential.
  • The client understands that investment performance affects policy value.
  • The client wants eligible investment choices governed by written rules.
  • The client wants cash value and lapse risk reviewed regularly.
Policy components

Insurance protection and market exposure are different parts of the policy

Variable universal life combines life insurance with investment options held through separate-account arrangements. Market movements can affect the investment component and cash value.

One policy

Premiums enter the policy

Charges support insurance protection and policy expenses

Remaining value may be allocated to variable subaccounts

Investment results affect policy value

Policy value and funding discipline influence long-term sustainability.

Insurance component

Policy protection

  • Death benefit subject to policy terms
  • Insurance charges and policy expenses
  • Policy funding and lapse considerations
Investment component

Variable subaccounts

  • Investment options available under the policy
  • Value can rise or fall with investment results
  • Allocation choices affect investment exposure

Illustrative only. Product design, charges, investment options and guarantees vary by insurer and contract.

02

Governance Review

01

Policy purpose: Protection need, ownership, beneficiaries, and planning role are defined.

02

Carrier and contract review: Provider quality, policy terms, investment options, loan rules, and reporting are assessed.

03

Investment menu: Eligible funds and managers are screened for purpose, liquidity, and suitability.

04

Allocation policy: Target weights, risk ranges, cash reserve, and rebalancing rules are documented.

05

Policy health: Cash value, surrender value, lapse margin, premiums, and investment results are reviewed.

03

Policy Review Indicators

  • Policy cash value and surrender value.
  • Premiums paid and future premium requirement.
  • Investment allocation by fund, asset class, and currency.
  • Lapse margin under lower return scenarios.
  • Loan balance where policy loans are used.
04

Balance Over Time

Variable Universal Life requires a high standard of governance because investment results and policy mechanics move together. The value lies in keeping protection and investment exposure in balance.

Service Enquiry

Review policy specifications, investment options, allocation rules and the long-term considerations relevant to a Variable Universal Life arrangement.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Tailored advisory

Alternative Investments

Selective access to strategies that can add diversification, income, protection, or long term value creation when governed with discipline.

The advisory view

Alternative investments can strengthen a portfolio when they are introduced for a clear purpose. They can also add complexity when liquidity, manager quality, structure, documentation and underlying asset risks are not examined with discipline. The starting point is therefore not the opportunity itself, but the role it is expected to play.

Hexagone Group reviews alternative allocations across hedge funds, structured products, private equity, private credit and private infrastructure. Each opportunity is considered through suitability, access path, manager or issuer quality, liquidity profile, documentation, risk contribution and fit within the wider portfolio.

The objective is to help clients assess specialist investments with clarity. Capital commitments, redemption terms, distributions, valuation points, financing structures and material asset-level risks should be understood before capital is committed.

01

Purpose of the Allocation

  • Strategies beyond traditional listed equities and bonds.
  • Defined exposure to private markets, specialist managers, or structured outcomes.
  • Better visibility on liquidity, capital calls, distributions, coupons, and counterparty risk.
  • A measured due diligence process before commitment.
  • A consolidated view of how alternatives affect the wider portfolio.
02

Path to Commitment

01

Role definition: The intended contribution is defined, such as income, diversification, protection, or long term growth.

02

Due diligence: Manager quality, issuer strength, strategy repeatability, liquidity, documentation, and operational standards are reviewed.

03

Implementation plan: Exposure size, cash flows, access path, and reason for inclusion are documented.

04

Ongoing oversight: Performance, risk, valuation, liquidity events, and next decisions are monitored.

03

Diligence Standards

  • Manager track record and investment process.
  • Issuer and counterparty strength where applicable.
  • Lock up periods, notice periods, redemption windows, and settlement terms.
  • Capital calls, distributions, coupons, maturities, and reinvestment rules.
  • Correlation, drawdown behaviour, and concentration inside the wider portfolio.
05

Selective Depth

Alternative investments should not make a portfolio harder to understand. Used selectively, they can add depth, but only when the client can see the reason, the risks, the liquidity, and the expected role.

Service Enquiry

Discuss specialist strategies through liquidity, time horizon, manager quality and their role within your wider portfolio.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Alternative Investments

Hedge Funds

Specialist manager strategies selected for role, discipline, liquidity terms, and behaviour across market conditions.

The advisory view

Hedge funds can serve several purposes inside a portfolio, from diversification and downside management to return seeking strategies with lower dependence on broad market direction. The value depends on manager quality, process repeatability, risk control, and clear liquidity terms.

Hexagone Group reviews hedge fund exposure by strategy type, manager process, operational standards, service providers, transparency, and fit within the wider allocation. The focus is how the strategy behaves, not only reported performance.

01

Where It Can Help

  • The client wants return streams that differ from traditional market beta.
  • The client wants portfolio behaviour assessed during periods of stress.
  • The client is comfortable with specialist managers and less frequent liquidity where appropriate.
  • The client wants manager selection supported by due diligence and ongoing review.
02

Manager Review Method

01

Strategy role: The allocation is defined for diversification, protection, alpha, or return smoothing.

02

Manager review: Process, team stability, risk management, operational controls, service providers, and alignment are assessed.

03

Liquidity review: Subscriptions, notice periods, gates, lock ups, side pockets, and redemption settlement are examined.

04

Portfolio fit: Exposure, factor sensitivity, concentration, and overlap with existing holdings are reviewed.

05

Monitoring: Performance attribution, drawdown, exposures, and any change in process or personnel are followed.

03

Liquidity and Control Points

  • Subscription frequency and notice period.
  • Redemption gates and suspension rights.
  • Side pocket treatment and valuation practice.
  • Service provider quality and operational controls.
  • Transparency of exposure, risk limits, and manager reporting.
04

Strategy Set

  • Global macro across rates, currencies, commodities, and equity indices.
  • Equity long short with controlled net and gross exposure.
  • Relative value strategies focused on market dislocations.
  • Event driven strategies around mergers, restructurings, and corporate actions.
  • Market neutral strategies seeking alpha with limited market direction.
  • Multi strategy platforms combining several specialist books under one risk system.
Educational view

“Hedge fund” describes a vehicle, not one investment strategy

Different hedge-fund strategies can seek returns from different market relationships, events and trading approaches. The strategy and manager matter more than the label alone.

Relative valueLooks for pricing differences between related instruments or markets.
Event drivenFocuses on corporate events such as restructurings, mergers or other catalysts.
MacroExpresses views across rates, currencies, commodities and other markets.
Equity long/shortCombines long and short equity positions under a defined manager process.
Multi-strategyAllocates across more than one strategy under a single manager or platform.

Educational only. Strategy labels do not indicate expected return, diversification benefit or level of risk.

05

Portfolio Role

The strongest hedge fund allocations are selected to improve portfolio behaviour, not to dominate the portfolio story.

Service Enquiry

Review strategy fit, manager discipline, liquidity terms and the role a hedge fund allocation may play within the wider portfolio.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Alternative Investments

Structured Products

Defined investment outcomes designed around reference assets, issuer strength, payoff terms, and maturity conditions.

The advisory view

Structured products can be useful when the client wants a defined payoff profile linked to specific reference assets. They may be designed for income, participation, conditional protection, or a combination of objectives. The quality of the structure depends on the clarity of its terms and the strength of its issuer.

Hexagone Group reviews structured products through payoff design, issuer comparison, documentation, booking method, observation dates, corporate actions, and secondary market options. Barriers, coupons, calls, participation rates, buffers, and maturity outcomes must be clear before commitment.

01

When Precision Matters

  • The client wants a defined outcome rather than direct market exposure.
  • The client wants income or participation linked to selected reference assets.
  • The client wants barriers, coupons, calls, and maturity outcomes explained clearly.
  • The client wants issuer terms compared before commitment.
  • The client needs observation dates, events, and secondary options monitored.
02

From Design to Redemption

01

Objective definition: The intended purpose is defined as income, participation, conditional protection, or a specific market view.

02

Payoff design: Barriers, coupons, participation, call features, maturity rules, and reference assets are reviewed under base and stress scenarios.

03

Issuer comparison: Banks are compared by credit strength, payoff terms, documentation quality, settlement process, and service standard.

04

Term sheet review: Definitions, observation dates, calculation agent terms, currency, and early redemption rules are checked.

05

Booking review: Subscription, account booking, settlement, and confirmation are reviewed until the position is recorded correctly.

06

Lifecycle review: Coupons, barrier events, calls, maturity, and secondary market options are monitored until exit or redemption.

03

Defined Outcomes

The discipline in structured products is to make the payoff simple to understand even when the instrument is technical. The client should know what can happen, when it can happen, and why it matters.

Simplified illustration

Why can a structured product behave differently from the underlying asset?

The payoff is determined by the note terms. Features such as barriers, participation and caps can change the outcome compared with owning the reference asset directly.

Simplified structured product payoff profileA conceptual payoff line shows downside exposure below a barrier, a protected or flat area between the barrier and reference level, participation above the reference level and a possible cap. No numerical terms are shown.Reference asset performanceIllustrative product outcomeBarrier, if applicableDownside exposureProtection or flat zoneParticipationCap, if applicableReference level
Below a barrier, if usedDownside exposure can apply according to the product terms.
Protected or flat zoneSome structures can alter the outcome over a defined range.
Participation zoneThe payoff can participate in gains according to the stated formula.
Cap, if usedSome products limit the maximum payoff.

ILLUSTRATIVE ONLY. NOT A FORECAST OR RECOMMENDATION. This is a simplified schematic, not a real product. Actual structures, protections, barriers, participation, caps, liquidity and issuer terms vary by product.

Partner Perspective

Defined outcomes require informed assessment

Structured products can bring a powerful additional layer to a global portfolio, creating tailored sources of return and income beyond traditional equity and bond markets.

Used strategically, they can enhance diversification, improve portfolio efficiency and capture opportunities across different market conditions, while protecting you from volatility.

The key lies in selecting the right structure, underlying assets and risk-return profile for each investor.

Key Considerations
Payoff StructureUnderlying AssetsRisk-Return ProfilePortfolio Role
Service Enquiry

Review payoff design, issuer considerations, documentation and lifecycle monitoring before considering a structured product allocation.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Alternative Investments

Private Equity

Long term exposure to private companies through disciplined manager selection, vintage planning, and cash flow control.

The advisory view

Private equity can provide access to value creation outside public markets, but it requires patience, manager selection, and disciplined pacing. Capital is usually committed before it is fully invested, and distributions arrive over several years. The programme therefore needs a clear funding plan from the outset.

Hexagone Group reviews private equity opportunities across primary funds, secondaries, and selected co investments where suitable. The review considers strategy, manager quality, track record, team stability, alignment, reporting, valuation approach, and expected cash flow pattern.

01

Investment Horizon

  • The client has a long term horizon and can tolerate illiquidity.
  • The client wants access to private company growth and specialist managers.
  • The client wants commitments paced across more than one vintage year.
  • The client needs capital calls and distributions mapped clearly.
  • The client wants manager selection supported by due diligence and monitoring.
02

Programme Construction

01

Allocation design: Target exposure, strategy mix, geography, sector preference, and acceptable illiquidity are defined.

02

Manager and access review: Primary funds, secondary opportunities, and co investments are assessed by process, alignment, terms, and governance.

03

Commitment planning: Expected capital calls, distributions, and liquidity reserves are mapped.

04

Portfolio monitoring: Valuations, cash flows, company exposure, sector concentration, and manager reporting are reviewed.

05

Exit review: Distributions, secondary sale options, extension requests, and reinvestment decisions are assessed.

03

Cash Flow Signals

  • Committed capital, called capital, and unfunded commitment.
  • Distributed to paid in capital and residual value to paid in capital.
  • Net internal rate of return and multiple on invested capital.
  • Exposure by vintage year, manager, sector, and geography.
  • Distribution pattern and remaining commitment profile.
Capital timing

Committed capital is not necessarily invested all at once

Private-equity funds commonly draw committed capital over time. Later, proceeds from realised investments may be distributed back to investors.

Illustrative timing only. Bars do not represent amounts, returns or expected performance. Capital-call and distribution timing varies by fund.

04

Long Term Discipline

Private equity rewards patience, but patience must be organised. Strong outcomes depend on manager selection, vintage discipline, and the ability to fund commitments without pressure.

Private Equity Perspective

Patience, selectivity and a long-term view

Long-term horizon Limited liquidity Capital at risk

Private equity provides investors with the opportunity to participate in long-term business growth and can offer diversification beyond traditional equities and bonds. It is generally more complex than traditional investments and is typically suited to investors with a long-term investment horizon who understand the associated risks and limited liquidity.

“Private equity should be approached with a long-term investment horizon and a clear understanding of its limited liquidity, restricted access to invested capital and higher risk, including the potential loss of capital.”
Andrea Iacono, Wealth Advisor

Andrea Iacono

Wealth Advisor

Service Enquiry

Discuss access, strategy, liquidity, time horizon and the role private equity may play within a broader portfolio.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Alternative Investments

Private Credit

Income focused private market exposure built on underwriting quality, seniority, collateral, and lender protection.

The advisory view

Private credit can provide a differentiated source of income when underwriting is exact and documentation is strong. The focus should never be headline yield alone. It should be the quality of the borrower, the position in the capital structure, the collateral, lender protections, and the behaviour of cash flows under stress.

Hexagone Group reviews private credit opportunities across senior secured lending, direct lending, asset backed lending, real estate debt, specialty finance, and opportunistic credit where suitable. The review considers manager process, loan documentation, diversification, valuation, default history, and recovery discipline.

01

Income With Discipline

  • The client wants income beyond traditional bond markets.
  • The client is prepared to accept less liquidity for stronger underwriting access.
  • The client wants exposure to seniority, collateral, and lending protections.
  • The client wants cash flow timing and reinvestment planned in advance.
  • The client wants manager selection and credit monitoring handled with discipline.
02

Credit Review Method

01

Strategy role: The position inside the income allocation is defined by seniority, sector, duration, and liquidity profile.

02

Manager review: Underwriting standards, team experience, origination quality, workout capability, and alignment are assessed.

03

Credit file review: Borrower quality, collateral coverage, leverage, interest coverage, lender protections, and documentation are examined.

04

Cash flow plan: Coupons, amortisation, maturities, funding needs, and reinvestment rules are mapped.

05

Monitoring: Defaults, impairments, valuation changes, loan events, and distributions are reviewed.

03

Credit Spectrum

  • Senior secured lending with first lien protection.
  • Unitranche lending with blended risk and return.
  • Asset backed lending supported by identifiable collateral or receivables.
  • Real estate debt for acquisition, development, or refinancing needs.
  • Specialty finance in defined lending niches.
  • Opportunistic credit during periods of market dislocation.
Financing position

Where does private credit sit in a company’s financing?

Private credit provides negotiated financing to a borrower. The loan’s seniority, security and documentation influence its position relative to other debt and equity.

Capital relationship
Private lender or fund
Loan capital
Borrower

The loan agreement sets interest, maturity, covenants, security and other terms. Those terms differ materially by transaction.

Simplified capital structure
Senior secured debtHigher contractual priority, often with security.
Senior unsecured debtSenior claim without the same collateral position.
Junior or subordinated debtRanks below senior obligations.
EquityResidual ownership claim.
Repayment priority generally runs from top to bottom. Priority does not remove credit risk.
04

Strength Behind the Income

Private credit should be judged by the quality of the structure behind the yield. The first question is not what it pays, but why it should pay reliably.

Senior Partner Perspective

Credit quality comes before headline yield

Private credit provides negotiated financing outside public markets across strategies such as senior secured lending, direct lending, asset-backed lending, real estate debt and specialty finance. Its role within a portfolio should be assessed through underwriting quality, seniority, collateral, documentation, liquidity and the strength of lender protections.

Credit assessment
UnderwritingSeniorityCollateralDocumentationLiquidityLender protections
Investment discipline

Private credit should not be assessed on headline yield alone. The quality of the underwriting, the borrower’s ability to service the debt, the position in the capital structure and the protections built into the documentation are what determine whether an opportunity deserves a place within a client’s broader portfolio.

David Palacci, Senior Partner
David PalacciSenior Partner
Service Enquiry

Assess private credit strategies through underwriting quality, seniority, documentation, liquidity and their role within the broader portfolio.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Alternative Investments

Private Infrastructure

Long-term exposure to essential assets and services assessed through manager quality, contractual cash flows, capital structure, operational resilience and portfolio fit.

The advisory view

Private infrastructure provides exposure to physical and digital assets that support economic activity and essential services. Depending on the strategy, this can include energy, utilities, transport, digital infrastructure and selected social infrastructure. These assets may have long operating lives and contractual or regulated revenue characteristics, but their risks vary significantly by sector, geography, financing structure and stage of development.

Hexagone Group approaches private infrastructure as a portfolio allocation rather than a thematic investment. Review focuses on the underlying assets, manager discipline, capital structure, contractual framework, valuation approach, liquidity, governance and the role the exposure is expected to play alongside the client's wider investments.

01

Real Assets With a Defined Purpose

Private infrastructure may be considered where:

  • the client has a long-term investment horizon
  • the client can accommodate limited liquidity
  • the portfolio requires differentiated exposure to real assets
  • the client wants to understand the relationship between contractual cash flows, asset utilisation and operating risk
  • the client wants infrastructure exposure reviewed alongside private equity, private credit and public-market investments
  • the investment can be assessed through a disciplined manager and asset-level due-diligence process

Infrastructure is not a single risk category. An operating regulated utility, a development-stage renewable project and a digital infrastructure platform can behave very differently. The investment case therefore begins with the asset and its economics, not the infrastructure label.

02

Infrastructure Review Method

01

Portfolio role. Define why infrastructure is being considered: diversification, long-duration exposure, income characteristics, real-asset exposure or access to specific structural themes.

02

Strategy and manager review. Assess the manager's experience, investment discipline, governance, sourcing capability, operating expertise, alignment and approach to asset ownership.

03

Asset-level review. Examine the nature of the underlying infrastructure, location, stage of development, counterparties, demand characteristics, operating history and material dependencies.

04

Capital structure. Review leverage, debt maturity, refinancing exposure, capital expenditure requirements and the position of investors within the structure.

05

Contract and revenue review. Consider concession arrangements, regulated revenues, contractual counterparties, pricing mechanisms, utilisation assumptions and sensitivity to changing demand or regulation.

06

Liquidity and cash-flow planning. Map capital calls, holding periods, distributions, reinvestment requirements and expected liquidity alongside the client's wider commitments.

07

Monitoring. Review material developments in operations, financing, valuation, governance, regulation, counterparties and portfolio concentration over time.

03

Infrastructure Segments

  • Energy & Transition Infrastructure

    Power generation, transmission, storage and related infrastructure where appropriate.

  • Utilities

    Essential networks and services such as water, electricity and other regulated or contracted utility infrastructure.

  • Transport

    Road, rail, ports, airports and selected transport-related assets.

  • Digital Infrastructure

    Data centres, fibre networks, communications infrastructure and related digital assets.

  • Social Infrastructure

    Selected assets supporting essential public or community services where suitable.

  • Specialist Infrastructure

    Sector-specific assets that require particular operating expertise, contractual analysis or technical understanding.

Availability depends on jurisdiction, provider access, structure and individual suitability.

Asset stage

Infrastructure risk changes as an asset moves through its life

A project under development has different execution and cash-flow characteristics from an established operating asset. The investment stage matters alongside the sector itself.

DevelopmentPlanning, permissions, contracts and financing are still being established.
ConstructionCapital is deployed while completion, budget and delivery risks remain active.
Operating assetThe asset is in service and operating performance can be assessed.
Mature assetFocus shifts toward long-term operation, maintenance and capital needs.
TransportEnergyDigital infrastructureUtilitiesWaste and selected social infrastructure where applicable

Illustrative only. Infrastructure projects and funds can have different contractual, market, construction, regulatory, leverage and liquidity risks.

04

Risk Is Asset-Specific

  • long holding periods and limited liquidity
  • construction and development risk where applicable
  • operating and maintenance risk
  • demand or utilisation risk
  • counterparty and contractual risk
  • leverage and refinancing risk
  • interest-rate sensitivity
  • valuation uncertainty in private markets
  • regulatory and political risk
  • currency exposure where assets and investors are in different currencies
  • technology and obsolescence risk, particularly in digital infrastructure
  • concentration by asset, manager, geography or sector
  • capital expenditure requirements
  • exit timing and secondary-market limitations

Essential services do not mean risk-free investments. The durability of an infrastructure asset depends on its economics, financing, contracts, operating model and the price paid for the exposure.

05

Building Infrastructure Exposure With Discipline

Private infrastructure can sit alongside private equity and private credit, but its portfolio role should be assessed independently. The appropriate exposure depends on existing real-asset holdings, liquidity requirements, unfunded commitments, manager concentration, geography, currency and the client's broader objectives.

  • strategy and sector allocation
  • core / core-plus / value-add characteristics where relevant
  • operating versus development-stage exposure
  • geography
  • manager concentration
  • vintage diversification where fund structures apply
  • leverage
  • currency
  • unfunded commitments
  • distribution expectations
  • valuation frequency
  • exit assumptions
06

Beyond the Asset

Infrastructure outcomes depend not only on the quality of the asset but also on the people and structures governing it. Manager capability, operating expertise, investment discipline, alignment, financing decisions and reporting standards can materially influence the investment experience.

  • manager experience across infrastructure cycles
  • operating and technical resources
  • governance
  • investment committee discipline
  • conflicts management
  • fee and incentive alignment
  • valuation governance
  • financing discipline
  • asset-management capability
  • reporting transparency
  • sustainability considerations where genuinely material to asset economics and risk
07

Long-Term Capital Requires Planning

Private infrastructure is generally considered a long-term allocation. Depending on the structure, investors may face multi-year holding periods, capital calls, restrictions on transfers and limited secondary-market liquidity. The allocation should therefore be considered alongside the client's wider liquidity needs and other private-market commitments.

Liquidity should be planned before commitment, not after capital is required elsewhere.

FAQ

Private Infrastructure Questions

What is private infrastructure?

Private infrastructure refers to investments in privately held or privately financed assets and businesses that provide essential physical or digital services. Depending on the strategy, these may include energy, utilities, transport, digital infrastructure and selected social infrastructure.

How does private infrastructure differ from private equity?

Private infrastructure focuses on assets and businesses associated with essential infrastructure and real assets, while private equity covers a broader range of privately owned companies. Infrastructure investments may have different operating, contractual, financing and liquidity characteristics, so the two allocations should be reviewed separately.

Is private infrastructure liquid?

Private infrastructure is generally a long-term and relatively illiquid investment. Liquidity depends on the structure, asset, fund terms and secondary-market conditions. Investors should understand capital-call obligations, holding periods and exit options before committing capital.

What does Hexagone Group review when considering private infrastructure?

Hexagone Group reviews the intended portfolio role, manager quality, underlying assets, contractual framework, capital structure, leverage, liquidity, governance, valuation approach, material risks and fit with the client's wider portfolio.

What are the main risks of private infrastructure?

Risks can include illiquidity, leverage, valuation uncertainty, construction or development risk, operating risk, demand risk, counterparty risk, regulation, refinancing, currency exposure and asset-specific technological or commercial change.

Can private infrastructure provide income?

Some infrastructure strategies may generate distributions from operating or contractual cash flows, but income is not guaranteed. Cash-flow characteristics depend on the asset, financing structure, contracts, operating performance and investment terms.

Service Enquiry

Review infrastructure strategy, manager quality, underlying assets, liquidity, capital structure and the role private infrastructure may play within the wider portfolio.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by client-appointed advisers where required.

Private infrastructure may involve significant risks, including illiquidity, valuation uncertainty, leverage, operational risk, development risk, counterparty risk and loss of capital.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, tax or real-estate advice. Hexagone Group does not provide tax advice.

Tailored advisory

Wealth Planning

Planning structures for protection, mobility, ownership, and succession, arranged with clarity across borders.

The advisory view

Wealth planning is most effective when personal objectives, asset ownership, protection needs, residence choices, and succession documents are considered together. The aim is not complexity. It is clarity that can be understood by the client, banks, trustees, insurers, legal advisers, and future decision makers.

Hexagone Group coordinates wealth planning with appropriate licensed partners where required. Advisory work may cover protection, residency and citizenship options, legal structuring, beneficiary language, and international wills so the wider wealth plan remains coherent.

The work begins with facts: assets, liabilities, jurisdictions, family arrangements, operating entities, banking relationships, and future intentions. From there, the planning structure can be designed, documented, and reviewed with precision.

01

Planning Priorities

  • Clear ownership and beneficiary arrangements across jurisdictions.
  • Protection aligned to liabilities, family needs, and planning horizons.
  • Residency or citizenship options assessed through practical recognition and obligations.
  • Companies, trusts, foundations, or other structures chosen for purpose and substance.
  • International wills and related documents aligned with asset location and family intent.
02

How the Plan Takes Shape

01

Balance sheet map: Assets, liabilities, entities, policies, bank accounts, jurisdictions, and key dependants are identified.

02

Objective setting: Protection, mobility, succession, control, reporting, and privacy needs are ranked by priority.

03

Professional coordination: Legal, insurance, residency, and corporate advisers are involved where required.

04

Design selection: Suitable policy, residency, entity, or document solutions are compared for fit and practicality.

05

Implementation support: Applications, policy documents, entity records, wills, and supporting evidence are organised with partners where required.

06

Review: Changes in residence, family situation, assets, or banking requirements are reflected in updated records.

04

Clarity When It Matters

A well designed plan should remain unobtrusive in daily life and precise when it matters. It should reduce uncertainty, not add another layer of administration.

Service Enquiry

Review protection, ownership, mobility and documentation priorities with the relevant professional partners where applicable.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Wealth Planning

Term Life Insurance

Straightforward protection sized to real liabilities, family needs, and the years that matter most.

The advisory view

Term life insurance is often the cleanest form of protection for a defined period. It can help cover mortgage liabilities, education needs, business obligations, income replacement, or family security during the years when protection is most needed.

Hexagone Group helps clients assess cover amounts, policy term, premium structure, currency, underwriting requirements, ownership, and beneficiary language through suitable providers. The objective is protection that is sufficient, understandable, and easy to maintain.

01

Defined Period Protection

  • The client wants protection for a mortgage, family income, or education obligation.
  • The client wants cover for a defined number of years rather than permanent insurance.
  • The client wants premiums matched to currency and cash flow.
  • The client wants beneficiaries and policy records written clearly.
Coverage period

Term insurance protects for a defined period

The defining feature is time. Cover applies during the policy term, subject to the policy remaining in force and its contractual conditions.

Policy startCoverage termTerm end
If the insured dies during the covered term, the policy may pay the stated death benefit to the beneficiary, subject to the policy terms and exclusions.
02

Protection Review Path

01

Needs analysis: Liabilities, income replacement, education funding, and time horizon are translated into a cover amount.

02

Policy selection: Term length, premium pattern, currency, optional benefits, and provider options are compared.

03

Underwriting and records: Medical evidence, financial documents, beneficiaries, and policy storage are coordinated with suitable providers.

03

Exact Cover

Protection is strongest when it is precise. The policy should answer a real liability, last for the correct period, and be easy for the family to evidence when needed.

Service Enquiry

Review cover amount, term length, currency, underwriting and beneficiary provisions within the wider protection plan.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Wealth Planning

Citizenship by Investment

Structured access to second citizenship options through eligibility review, documentation, and licensed programme partners.

The advisory view

Citizenship by investment can support mobility, security, and continuity when the selected option is suitable and recognised in practice. The quality of the application depends on eligibility, financial evidence, document accuracy, timing, and the credibility of the programme provider.

Hexagone Group works with licensed partners where required to help clients assess available options, prepare documentation, coordinate milestones, and maintain records after issuance. The process must be orderly from the first screening to passport delivery.

01

Mobility and Recognition

  • The client wants additional mobility and optionality for the family.
  • The client wants a second citizenship option assessed against eligibility and recognition.
  • The client needs financial evidence prepared to a high standard.
  • The client wants a clear process for application, issuance, renewal, and family updates.
02

Application Review Path

01

Objective review: Mobility, family coverage, timing, access needs, and long term use are clarified.

02

Programme comparison: Jurisdictions are compared for eligibility, reputation, recognition, contribution requirements, and processing standards.

03

Pre screening: Background, financial evidence, dependants, and suitability are reviewed with licensed partners.

04

Document preparation: Identification, civil records, bank references, corporate records, and financial evidence are assembled.

05

Submission support: Application forms, translations, attestations, and provider requirements are coordinated.

06

Decision and issuance: Approval stages, oath or certificate steps, passport issuance, and delivery are tracked with partners.

07

Aftercare: Renewals, family additions, address changes, and document records are diarised and maintained.

03

Records Beyond Approval

In citizenship planning, records matter as much as the option selected. A clean file protects the value of the approval long after the passport is issued.

Service Enquiry

Review eligibility, documentation, financial evidence and programme considerations with licensed providers and professional partners where required.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Wealth Planning

Residency by Investment

Residence rights arranged around practical eligibility, credible obligations, and clean records.

The advisory view

Residency by investment can support lifestyle, education, business, and family planning when the selected option fits the household actual movements and obligations. The best programme is not always the most visible one. It is the one the client can maintain properly.

Hexagone Group works with licensed providers where required to help clients compare jurisdictions, prepare evidence, coordinate applications, and monitor renewals. The focus is practical recognition, documentation quality, stay requirements, and family coverage.

01

Practical Residence Planning

  • The client wants residence rights for lifestyle, education, business, or family reasons.
  • The client wants to compare options by obligations, recognition, timing, and renewal rules.
  • The client needs property, banking, insurance, or local evidence arranged correctly through appropriate partners.
  • The client wants a clear renewal record.

Residence Review Path

01

Jurisdiction review

Residence options are compared for eligibility, stay rules, family coverage, timing and practical recognition.

02

Obligation analysis

Physical presence, property, insurance and renewal requirements are reviewed with partners where required.

03

Liveable Obligations

Residency planning works best when the chosen programme fits real life. Obligations should be clear, credible, and manageable from the beginning.

Service Enquiry

Compare residency options, documentation requirements, local obligations and renewal considerations with the relevant professional partners where required.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Wealth Planning

Wealth Structuring

Ownership and governance structures designed for clarity, substance, administration, and long term use.

The advisory view

Wealth structuring brings assets into an ownership arrangement that can be administered clearly and reviewed with confidence. The structure may involve companies, trusts, foundations, partnerships, or other legal arrangements, depending on the client and professional advice.

Hexagone Group coordinates with legal, fiduciary, banking, and administrative partners where required. The aim is to select structures that have a clear purpose, credible substance, practical governance, and records that can withstand review.

01

Ownership and Governance Clarity

  • The client owns assets across jurisdictions or through several entities.
  • The client wants clearer ownership, governance, and succession planning.
  • The client needs substance, administration, and reporting to match the stated purpose.
  • The client wants banking, accounting, and legal records organised under one view.
Ownership view

A structure changes how ownership and control are organised

The useful question is not whether a structure is “better”, but who owns it, who can act, what assets it holds and how succession is documented.

Individual or family

Ownership or holding structure

Legal ownershipControl and governanceAuthorised decision-makersDocumentation and records
Investment accountsBusiness interestsPropertyOther investments
Beneficiary and succession arrangements are reviewed alongside the ownership structure with appropriately qualified legal advisers where required.

This is a conceptual ownership map only. It does not provide legal or tax advice and does not imply that any particular structure is suitable.

02

Structure Review Path

01

Asset map: Assets, entities, bank accounts, policies, liabilities, and jurisdictions are documented.

02

Purpose review: Control, succession, investment, reporting, privacy, and operating needs are prioritised.

03

Professional advice: Legal, fiduciary, and corporate service providers are engaged where required.

04

Structure selection: Companies, trusts, foundations, partnerships, or other arrangements are compared for fit.

05

Governance design: Directors, trustees, protectors, signatories, decision rules, and reporting lines are defined.

06

Administration setup: Banking, accounting, filings, registers, and resolutions are coordinated with partners.

07

Review and update: Changes in assets, residence, family circumstances, or banking requirements are reflected in records.

03

Restraint and Proof

Good structuring is restrained. It uses the right level of planning, supported by records that prove the structure works in practice.

Service Enquiry

Map assets, governance priorities and documentation while coordinating the relevant legal and other professional advisers where required.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Wealth Planning

International Wills

Estate documents aligned with asset location, family intent, and recognition across relevant jurisdictions.

The advisory view

International wills help ensure that instructions can be understood by courts, banks, trustees, insurers, and advisers in the jurisdictions where assets are held. The objective is not simply to have a document. It is to have a document set that works in practice.

Hexagone Group coordinates with local legal advisers where required to help clients map assets, align beneficiary intent, prepare suitable documents, and maintain records. Primary wills, local wills, letters of wishes, policy beneficiaries, and company or trust documents should not contradict one another.

01

Clarity Across Jurisdictions

  • The client holds assets in more than one country.
  • The client has banking, property, company, trust, insurance, or investment arrangements across borders.
  • The client wants beneficiary intent to be clear and consistent.
  • The client wants signing, storage, and future updates organised properly.
02

Document Review Path

01

Asset inventory

Accounts, properties, companies, policies, and personal assets are mapped by country and ownership type.

02

Jurisdiction review

Relevant succession rules, recognition requirements, and possible conflicts are reviewed with legal advisers.

03

Document design

Primary wills, local wills, letters of wishes, and beneficiary designations are aligned.

04

Signing plan

Witnessing, notarisation, translations, apostille, and storage requirements are arranged with legal advisers where required.

05

Review control

Life events, new assets, residence changes, and family changes trigger document updates.

03

One Consistent Message

International estate planning should remove ambiguity. The documents should tell the same story in every jurisdiction that matters.

Service Enquiry

Map cross-border assets, beneficiary intentions and documentation while coordinating appropriately qualified legal advisers where required.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Tailored advisory

Global Properties

Property advisory and partner coordination for international clients seeking disciplined review, clear diligence, and measured decision making.

The advisory view

Property decisions are rarely only financial. They may involve lifestyle, education, residency, portfolio diversification, financing, and family planning. A good advisory process brings these factors into one clear view before the client moves toward a decision.

Hexagone Group provides property related advisory review and coordination with independent partners where required. Local agents, legal advisers, lenders, surveyors, valuers, and other specialists may be involved according to the market and the nature of the matter.

Our role is to help the client compare markets, understand the structure of an opportunity, review supporting evidence, and keep partner responsibilities clear. The work is advisory in nature and designed to support informed decisions, not to replace local licensed professionals.

01

Property in the Wider Plan

  • A clearer way to compare property opportunities across markets.
  • Independent guidance before making an acquisition or sale decision.
  • Partner coordination for diligence, financing review, and specialist input where required.
  • Access to listed, unlisted, and private real estate options where suitable.
  • A consolidated view of property as part of the wider wealth plan.
02

Advisory Path

01

Brief: Purpose, location preference, budget, financing needs, time horizon, income expectations, and lifestyle requirements are defined.

02

Market comparison: Locations are compared by price levels, liquidity, local practice, financing conditions, and stock quality.

03

Opportunity review: Selected opportunities are assessed through title, counterparty profile, technical information, comparable sales, and rental evidence with partners where needed.

04

Financing and partner input: Lending options, local advisers, offer terms, and professional reports are reviewed before the client proceeds.

05

Ongoing perspective: Ownership records, financing dates, leasing assumptions, and potential exit paths are kept under review as part of the wider plan.

03

What We Clarify

  • Acquisition purpose, whether residence, lifestyle, income, diversification, or long term family asset.
  • Ownership profile, including maintenance obligations, financing, and local administration.
  • Liquidity and likely time to sell in normal and weaker markets.
  • Rental assumptions, vacancy, management requirements, and local rules.
  • Financing terms, loan to value, rate type, lending conditions, and refinancing risk.
05

Evidence Before Emotion

Property should be approached with the same discipline as any other major allocation. The asset may be tangible, but the decision still depends on evidence, structure, and professional review.

Service Enquiry

Discuss property objectives, market priorities, financing considerations and the support required across the process.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Global Properties

European Property Intermediation

Advisory support for acquisitions and sales across selected European property markets through appropriate local partners.

The advisory view

European property markets differ sharply by country, city, legal practice, financing conditions, and local negotiation culture. Advisory intermediation brings order to the process by helping clients review the market, counterparties, diligence points, valuation evidence, financing terms, and local partner responsibilities.

Hexagone Group supports clients alongside trusted partners where required. The focus is discretion, evidence, and a clear advisory record from first brief to decision.

01

Market Specific Guidance

  • The client wants to buy or sell property in Europe.
  • The client wants local market insight with central advisory coordination.
  • The client needs price discovery supported by comparable evidence.
  • The client wants legal, technical, financing, and completion requirements reviewed clearly.
02

Intermediation Path

01

Market brief

Location, property type, budget, use case, financing, and time horizon are defined.

02

Partner mapping

Agents, legal advisers, surveyors, valuers, and notaries are identified where required.

03

Review Areas

  • Title and ownership history.
  • Planning and permitted use.
  • Building condition and capital expenditure needs.
  • Comparable sales and rental evidence.
  • Transaction obligations.
  • Financing conditions and completion timetable.
04

Verification Before Access

In European property, quality of process often determines quality of outcome. Access matters, but verification matters more.

Service Enquiry

Review market priorities, local partners, due diligence, financing considerations and completion requirements for a European property search.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Global Properties

Global Property Assistance

Advisory coordination for international property comparison, partner input, and decision records.

The advisory view

A global property search can quickly become scattered when several markets, agents, advisers, lenders, and time zones are involved. Global Property Assistance gives the client one organised advisory process across locations.

Hexagone Group helps translate the client brief into a practical comparison method, where markets are compared, opportunities are filtered, documents are collected, and partner responsibilities are kept clear.

01

Advisory Coordination

  • The client is comparing more than one market or city.
  • The client needs help coordinating agents, legal advisers, lenders, and local advisers through an advisory process.
  • The client wants one record of options, terms, evidence, and next steps.
02

How the Review Is Managed

01

Search brief: Objectives, budget, location, lifestyle needs, income expectations, and constraints are recorded.

02

Market and opportunity comparison: Selected opportunities are compared in a consistent format across locations.

03

Partner input: Agents, legal advisers, lenders, and technical advisers provide local information where required.

04

Decision record: Offer terms, diligence points, financing considerations, and outstanding questions are summarised for the client.

03

Advisory Output

  • A clear comparison of markets and selected opportunities.
  • A document checklist for each property.
  • A timeline of offer, diligence, financing, and completion steps.
  • A record of partner responsibilities and open points.
04

Measured Comparison

The value of global assistance is not volume. It is the ability to reduce scattered options into a small number of decisions that can be compared properly.

Service Enquiry

Coordinate market comparison, opportunity review, local partners and the decision records required across an international property process.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Global Properties

Off Plan Property Intermediation

Early stage development access reviewed through developer quality, contract terms, payment schedule, and delivery risk.

The advisory view

Off plan property can offer access to new developments before completion, but it also requires a higher level of diligence. The asset is not yet delivered, so developer strength, funding, construction progress, contract protections, and exit rules become central.

Hexagone Group assists through advisory review of developer profile, contract points with independent legal advisers, payment schedule, delivery risk, financing readiness, and final stage planning. Technical specialists may be involved where required.

01

Before Completion, Discipline Matters

  • The client wants access to a new development before completion.
  • The client wants developer track record and funding reviewed.
  • The client wants stage payments aligned with actual construction progress.
  • The client needs contract terms, assignment rules, and delivery risk explained.
  • The client wants leasing, resale, or completion readiness considered before the final stage.
02

Seven Stage Review

01

Development brief: Location, unit type, price, purpose, completion timing, and exit intention are defined.

02

Developer review: Track record, financial strength, past delivery, reputation, and project funding are assessed.

03

Commercial comparison: Price per square metre, specification, ongoing obligations, rental evidence, and comparable launches are reviewed.

04

Contract review: Deposit, stage payments, long stop date, variation rights, penalties, warranties, and escrow mechanics are examined with legal advisers where required.

05

Progress review: Developer updates, milestone evidence, and technical partner input are reviewed against the expected delivery path.

06

Completion readiness: Valuation, financing, registration requirements, insurance, and local administration are considered with partners.

07

Exit or lease view: Assignment, resale, rental licensing, management assumptions, and first year cash flow are considered.

Two-track timeline

The contract and the building do not progress on the same track

Off-plan purchases require attention to both the buyer’s contractual obligations and the developer’s construction milestones.

Client and contract
Reservation
Contract review
Funding milestones
Completion documents
Handover obligations
Development
Project launch
Construction
Progress milestones
Completion
Handover
Exact payment schedules, completion dates, contractual rights and developer obligations depend on the project and contract.
03

Forward Commitment

Off plan property should not be treated as a simple reservation. It is a forward commitment, and the discipline belongs before the first signature.

Service Enquiry

Review developer quality, contract terms, construction milestones, financing considerations and completion readiness before proceeding with an off-plan opportunity.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Global Properties

Mortgage Assistance

Financing review arranged through borrower preparation, lender comparison, documentation, and approval tracking with suitable providers.

The advisory view

Mortgage terms shape the full flexibility of property ownership. The lowest headline rate is not always the best choice once currency, loan term, repayment structure, lending conditions, prepayment rules, and refinancing risk are considered.

Hexagone Group provides advisory review on lender ready files, financing options, documentation requirements, and approval progress through suitable providers. The objective is a financing structure that matches the asset, income profile, and intended ownership horizon.

01

Financing That Fits Ownership

  • The client wants to finance or refinance a property.
  • The client needs lender options matched to residence, income, and property type.
  • The client wants rate, term, margin, structure, and flexibility compared properly.
  • The client wants approval conditions and completion funding monitored.
02

Financing Path

01

Borrower profile: Income, assets, liabilities, residence, currency, and existing debt are organised for lender review.

02

Lender shortlist: Banks and lenders are compared by appetite, rate type, loan to value, service quality, and approval conditions.

03

Term review: Fixed, variable, repayment, interest only, prepayment rules, and loan structure are compared over the expected holding period.

04

Application and valuation: Documents, valuation, credit questions, legal requirements, and conditions are coordinated.

05

Completion record: Offer, drawdown, payment schedule, account access, and refinancing dates are recorded.

Financing comparison

Two loan offers can differ in more than the headline rate

A useful comparison considers how the financing fits the borrower, the property and the wider ownership plan.

Comparison point
What to review
Loan-to-value
Permitted leverage and the equity contribution required by the lender.
Currency
Loan currency in relation to income, assets and the property purchase currency.
Interest structure
Fixed, variable or other interest structure, subject to the lender terms.
Tenor and repayment
Maturity, amortisation method and repayment profile.
Conditions
Underwriting, valuation, documentation and approval requirements.

Illustrative comparison framework only. Lender appetite, approval, rates, terms and availability vary and are not guaranteed.

03

Support the Asset

Good financing should support the property decision, not dominate it. The right structure is the one that remains suitable after the purchase is complete.

Service Enquiry

Review lender appetite, rate structure, documentation, approval conditions and completion funding within the wider property process.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Global Properties

REITs and SCPI

Real estate exposure through listed and unlisted professionally managed structures, reviewed for income, diversification, quality, and liquidity.

The advisory view

REITs and SCPI can provide access to real estate without the administration of direct ownership. They may offer diversification across tenants, sectors, and locations, but they still require selection discipline and a clear understanding of liquidity, valuation, and income policy.

Hexagone Group reviews listed and unlisted real estate exposure through manager quality, asset mix, distribution history, platform fit, currency, and liquidity conditions. The key is to understand what sits behind the yield.

01

Managed Real Estate Exposure

  • The client wants property exposure without direct ownership administration.
  • The client wants income and diversification across sectors or geographies.
  • The client wants liquidity and valuation rules understood before allocation.
  • The client wants manager quality reviewed in detail.
Indirect property exposure

The investor owns shares or units, not the individual buildings

REITs and SCPIs pool investor capital into property portfolios. The vehicle, manager, pricing and liquidity mechanism matter alongside the underlying properties.

InvestorsHold shares or units in the vehicle.
REIT or SCPI vehicleThe vehicle holds the property interests and is managed under its governing rules.
Property portfolioIncome-producing buildings or other permitted real-estate assets.
Property incomeRental and other property income may support distributions, which are not guaranteed.
Publicly traded REIT
SCPI
Trading
Shares trade on a public exchange.
Units are not exchange-listed in the same way.
Price formation
Market price changes during exchange trading.
Subscription, withdrawal or secondary-market pricing follows the SCPI’s rules and structure.
Liquidity
Exchange trading generally provides more immediate market access, subject to market conditions.
Liquidity can be lower and withdrawal or sale timing can depend on available counterparties and the SCPI structure.

Neither distributions nor capital value are guaranteed. Specific REIT and SCPI terms, fees, liquidity and portfolio characteristics vary.

02

Review Method

01

Universe review: Listed and unlisted options are compared by asset type, geography, sector, and access path.

02

Manager and asset review: Stewardship, tenant quality, lease profile, debt, occupancy, and track record are assessed.

03

Income review: Distribution policy, payout coverage, currency, and professional adviser input are examined where required.

04

Liquidity review: Trading volume, dealing windows, settlement terms, valuation method, and redemption rules are clarified.

03

Metrics Under Review

  • Net asset value and market price where applicable.
  • Distribution yield and coverage.
  • Occupancy rate and lease duration.
  • Sector and geography exposure.
  • Leverage at the structure level.
  • Dealing frequency and settlement timing.
04

Understand What Sits Behind Yield

Real estate exposure does not need to be direct to be meaningful. The discipline is to understand the assets, the manager, the income, and the liquidity before allocating.

Wealth Management Perspective

Real estate exposure without direct ownership

REITs and SCPIs provide access to diversified real estate portfolios without the operational responsibilities of direct property ownership. Within a broader allocation, they can contribute income and diversification alongside traditional asset classes such as equities and bonds, while giving investors exposure to different segments of the property market.

IncomeDiversificationReal Estate Exposure
Long-Term Perspective

REITs and SCPIs should be considered with a long-term perspective. They can provide access to real estate exposure without the burden of managing property directly, while still requiring careful consideration of liquidity, portfolio fit and the underlying assets.

Benoit Sureau
Benoit SureauVice President, Wealth Management
Service Enquiry

Assess REITs and SCPI through manager quality, underlying assets, income characteristics and liquidity terms before considering their portfolio role.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Global Properties

Private Real Estate

Selective private opportunities reviewed through sponsor quality, capital structure, underwriting, and exit planning.

The advisory view

Private real estate can offer access to opportunities that are not available through listed markets, but it demands strong due diligence. Sponsor quality, asset location, lease profile, capital structure, leverage, governance, and exit path all shape the final outcome.

Hexagone Group assesses private real estate opportunities with attention to sponsor alignment, transaction terms, cash flow assumptions, downside scenarios, financing, reporting, and exit optionality. The purpose is to understand both the asset and the structure around it.

01

Private Access, Documented Discipline

  • The client wants access to private real estate opportunities.
  • The client is comfortable with lower liquidity and longer holding periods.
  • The client wants sponsor and transaction due diligence before commitment.
  • The client wants underwriting, cash flow, leverage, and exit paths reviewed clearly.
02

Investment Review

01

Opportunity review: Asset type, location, strategy, holding period, expected income, and return profile are defined.

02

Sponsor diligence: Track record, capital at risk, governance, reporting, and treatment of investors are assessed.

03

Transaction review: Purchase price, financing, leverage, lending conditions, legal terms, control rights, and exit rights are examined.

04

Underwriting: Rent, vacancy, operating assumptions, capital expenditure, debt service, and exit value assumptions are tested.

05

Progress review: Leasing, valuation, loan position, distributions, capital expenditure, and reporting are reviewed.

06

Exit planning: Sale, refinance, recapitalisation, or extension options are considered before the hold period ends.

03

Key Planning Metrics

  • Purchase price and price per square metre.
  • Loan to value and debt service coverage.
  • Net operating income and occupancy.
  • Capital expenditure reserve.
  • Distribution yield and cash flow coverage.
  • Exit cap rate and valuation sensitivity.
Property economics

How does capital become property cash flow?

Private real-estate returns depend on both the financing structure and the property’s actual operating economics. The asset and the capital structure need to be reviewed together.

Investor equityCapital contributed by investors.
Debt financingBorrowed capital subject to lender terms and repayment obligations.

Property asset

Rental or property income+
Operating costs and reserves−
Capital expenditure−
Financing costs and debt service−
Net cash available=
HoldRefinanceSale or other exit

Illustrative only. This diagram does not show expected returns, IRR or distributions. Actual cash flows, leverage, costs and exit options depend on the asset and transaction.

04

Structure and Asset Together

Private real estate is strongest when the structure is as thoroughly reviewed as the asset. The building matters, but so do the sponsor, terms, leverage, and exit rights.

Service Enquiry

Review sponsor quality, underwriting assumptions, capital structure, cash flows, governance and potential exit paths within a private real-estate opportunity.

Start a Conversation
Important Information

Availability and suitability vary by jurisdiction, client circumstances, provider requirements, and the nature of the proposed arrangement.

Hexagone Group acts in an advisory capacity. Specialist services are handled by independent licensed partners or by the client appointed advisers where required.

This content is general information only and should not be relied upon as legal, investment, insurance, lending, residency, citizenship, or real estate advice.

Insights

Perspective for better decisions.

Research and practical guidance on the structures, risks, and decision points that matter to international clients: written to clarify complex subjects without adding noise.

Solar and wind energy infrastructure supporting the energy transition
Advisory Portfolio Guidance

Impact Investing: Aligning Wealth with Purpose

Impact investing aims to generate positive social and environmental outcomes alongside financial returns.

Read insight →
Kirchberg district in Luxembourg City with modern financial architecture and tram
Private Wealth Advisory

Luxembourg Security

Luxembourg offers unique levels of investor protection, an AAA rating, and international portability.

Read insight →
Hands measuring an architectural model with precision
Advisory Portfolio Guidance

Tailored Wealth Strategies for the Modern Investor

Crafting strategies that reflect your individual goals, risk tolerance, and aspirations.

Read insight →
New York Stock Exchange facade on Wall Street
Advisory Portfolio Guidance

Protecting Wealth Amid Market Volatility

Safeguarding your financial future requires a proactive and strategic approach.

Read insight →
Aerial cityscape combining residential and commercial property types
Properties Portfolio

Building a Diversified Real Estate Portfolio

Diversification helps mitigate risk, enhance returns, and support long-term goals.

Read insight →
Eco-friendly building with integrated green roofing
Properties Portfolio

Incorporating Sustainable Properties in Your Portfolio

Green and energy-efficient properties can offer long-term cost savings and resilience.

Read insight →
Intergenerational hands expressing support, protection and continuity
Private Wealth Advisory

Family Protection: The Cornerstone of Wealth Management

Safeguarding family ties and preserving legacies is a responsibility, not just a priority.

Read insight →
Advisory Portfolio Guidance

Impact Investing: Aligning Wealth with Purpose

Impact investing aims to generate positive social and environmental outcomes alongside financial returns.

Solar and wind energy infrastructure supporting the energy transition

Understanding Impact Investing

Impact investing places an explicit social or environmental objective alongside the financial objective of an investment. The mandate therefore has two dimensions to assess: whether the investment can deliver an appropriate risk-adjusted return, and whether the intended impact is identifiable and measurable.

The opportunity set is broad. It can include public or private equity, debt, specialist funds and real assets such as renewable-energy infrastructure, sustainable property, conservation or projects designed to expand access to essential services. The structure selected should still fit the investor’s liquidity needs, time horizon and tolerance for loss.

Defining the Outcome Before Selecting the Investment

A disciplined process begins by defining the outcome the investor actually wants to support. Climate transition, education, healthcare, economic inclusion and sustainable cities may all qualify as impact themes, but they involve different drivers, risks and measurement frameworks.

Clear priorities make it easier to distinguish a genuine impact allocation from a conventional investment carrying a broad sustainability label. They also make due diligence more focused: the investor can test whether the manager’s mandate, portfolio construction and reporting methodology are consistent with the stated objective.

Benefits and Portfolio Role

An impact allocation can broaden diversification by introducing exposures that may not be represented in a traditional portfolio. Private-market projects, specialist debt and real assets can behave differently from listed equities and government bonds, although they may also introduce greater illiquidity and valuation complexity.

For investors who want their capital to reflect personal values, the additional benefit is intentionality. That does not remove the need to compare expected returns, fees and downside risk with conventional alternatives. Impact is most useful when it is incorporated into the same investment-governance process as every other allocation.

Risks, Measurement and Due Diligence

Impact measurement is one of the most important challenges. Outcomes may be described using different metrics, time periods and methodologies, making direct comparison difficult. Investors should look for clearly defined targets, credible baselines, transparent reporting and a process for explaining outcomes that fall short of expectations.

Investment risks remain fully relevant. Emerging technologies can face regulatory and execution risk; private assets may be difficult to sell; projects may depend on long-term contracts or financing; and some strategies can be exposed to concentration. Due diligence should cover both the impact thesis and the underlying economics.

Integrating Impact into a Wider Strategy

Impact investing does not need to be treated as a separate portfolio. It can be integrated progressively by identifying suitable themes, deciding what role each allocation should play, setting exposure limits and monitoring both financial and impact results.

The review process should ask whether the investment continues to meet the original objective, whether its risk profile has changed and whether reported outcomes remain credible. This creates a repeatable framework in which purpose and portfolio discipline reinforce one another.

References

The official Hexagone Group article cites academic and industry work on impact investing, sustainability and impact measurement. The source article remains the governing editorial reference for this page.

Implementation Choices

Impact exposure can be introduced through listed strategies, specialist funds, private equity, private debt, green or sustainability-linked bonds and direct real assets. Each route offers a different combination of liquidity, transparency, governance and measurement.

Investors should decide whether the objective is broad alignment across a portfolio or a targeted allocation to a small number of measurable themes. That decision influences manager selection and the amount of monitoring required.

Monitoring Financial and Impact Outcomes

A review should consider financial performance and impact performance separately before bringing them together. An investment can meet its impact target but fail economically, or deliver an attractive return while missing its stated impact objective.

A clear scorecard helps preserve discipline. The original goals, measurement method, reporting frequency and acceptable trade-offs should be documented at the start so that later assessment is not shaped only by the outcome.

Source

Editorial subject and source structure verified against Hexagone Group. This mockup uses original editorial wording while preserving the source topic, structure and substantive points.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.

Important Information

This article provides general information only. It does not constitute legal, investment, insurance, lending, residency, citizenship, real estate, or other professional advice. Availability and suitability depend on jurisdiction, client circumstances, and provider requirements.

Private Wealth Advisory

Luxembourg Security

Luxembourg offers unique levels of investor protection, an AAA rating, and international portability.

Kirchberg district in Luxembourg City with modern financial architecture and tram

Luxembourg as a Cross-Border Financial Centre

Luxembourg is widely used for international wealth and insurance structures because it combines a mature European financial-services ecosystem with cross-border portability and a regulatory framework designed for internationally held assets.

For clients, the relevant question is not whether a jurisdiction is prestigious, but how the legal structure, custody arrangements and policyholder protections work in practice. Those details determine how assets are held, who controls them and what happens if an institution encounters difficulty.

The Triangle of Security

A central feature of Luxembourg life-insurance protection is the separation of roles between the insurer, the approved custodian bank and the insurance regulator. The regulatory framework is designed so that assets representing policyholder liabilities are held separately from the insurer’s own operating assets.

The tripartite relationship creates additional oversight over custody. In a stress event, the regulator has powers designed to protect the segregated assets and limit movements that could prejudice policyholders. This structural separation is one of the reasons Luxembourg is frequently considered for cross-border insurance-based wealth planning.

The Super-Privilege Principle

Luxembourg also provides a preferential claim for policyholders over certain assets representing insurance liabilities if an insurer fails. This priority is commonly referred to as the super privilege.

It is important to understand the scope and limits of any protection rather than treating the label as a guarantee against every form of risk. Product structure, insurer quality, custodian arrangements and the underlying investments remain part of the due-diligence process.

Portability and International Planning

For internationally mobile clients, portability can matter as much as investment selection. A structure that remains workable after a change of residence can reduce the need to rebuild arrangements every time the family relocates.

Cross-border suitability must still be checked whenever residence, citizenship, beneficiaries or asset locations change. A Luxembourg solution can be useful in the right circumstances, but it should be assessed in the context of the client’s full legal and financial position.

Practical Review Questions

Before establishing a structure, investors should understand the insurer, custodian, policy terms, eligible asset universe, liquidity, charges, beneficiary arrangements and the consequences of surrender or relocation. Independent legal and tax advice may be required in each relevant jurisdiction.

Due Diligence Beyond the Jurisdiction

Luxembourg’s framework is only one layer of the decision. Investors should still assess the insurer, the custodian, the policy wording, the investment assets held within the contract and the parties responsible for administration.

Charges, surrender conditions, investment restrictions and beneficiary provisions can materially affect outcomes. Protection features should be understood in legal terms rather than treated as a substitute for normal product and counterparty due diligence.

Review After a Change of Residence

International portability is valuable only when the structure remains suitable in the client’s new jurisdiction. A move can change reporting, tax treatment, permitted investments or the way beneficiaries are treated.

For that reason, cross-border insurance structures should be reviewed before relocation and whenever the family’s residence, citizenship or succession arrangements change.

Source

Editorial subject and source structure verified against Hexagone Group. This mockup uses original editorial wording while preserving the source topic, structure and substantive points.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.
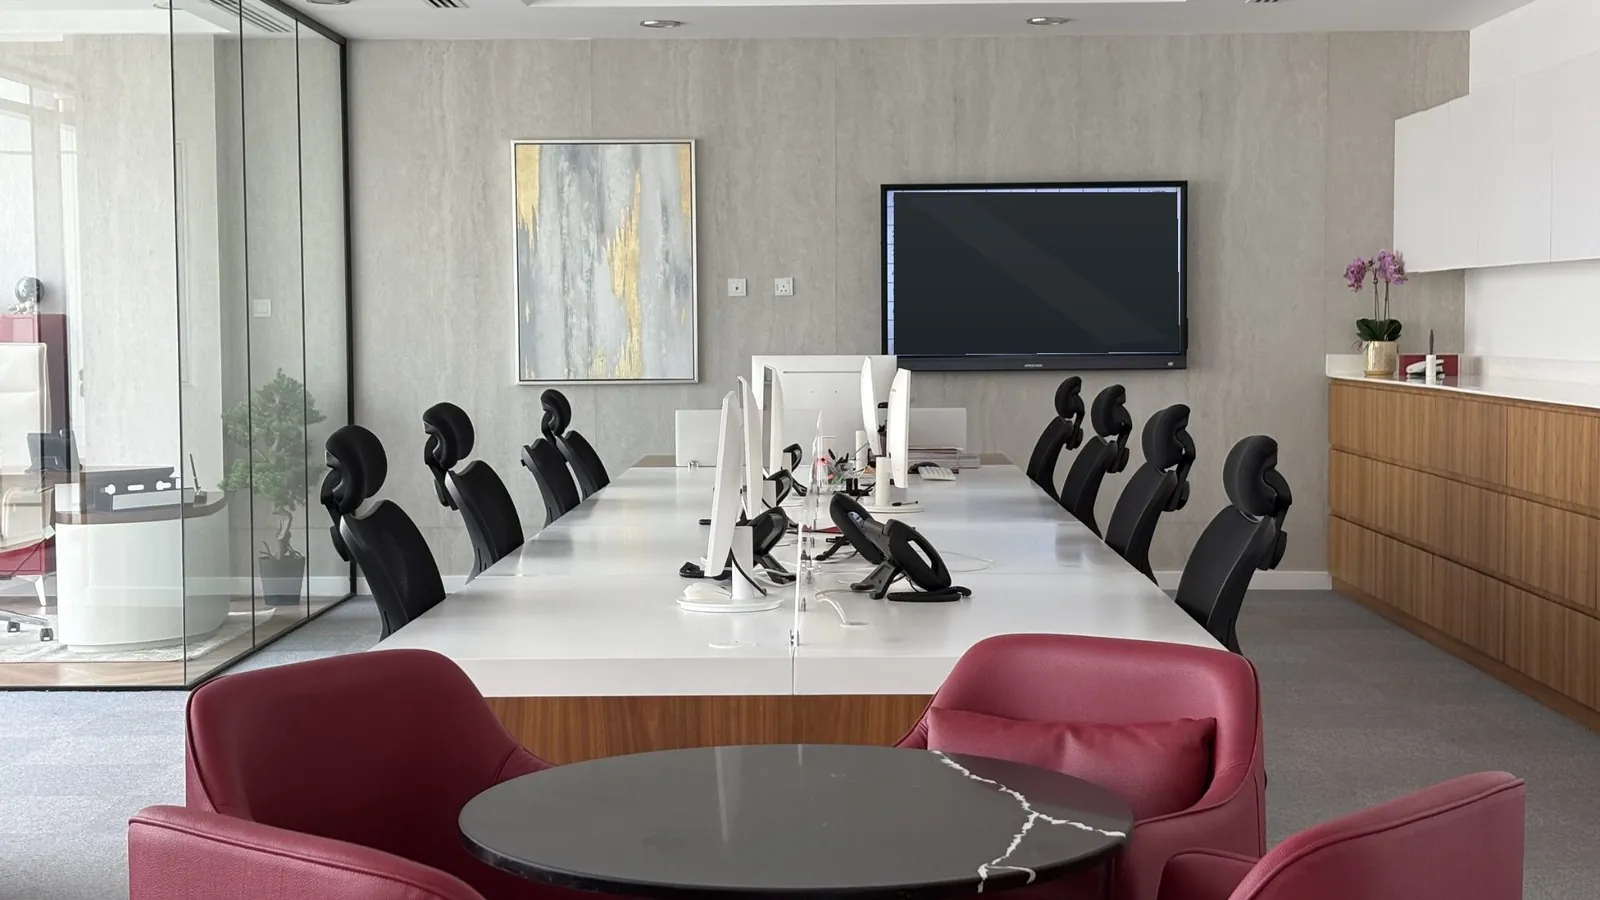
Important Information

This article provides general information only. It does not constitute legal, investment, insurance, lending, residency, citizenship, real estate, or other professional advice. Availability and suitability depend on jurisdiction, client circumstances, and provider requirements.

Advisory Portfolio Guidance

Tailored Wealth Strategies for the Modern Investor

Crafting strategies that reflect your individual goals, risk tolerance, and aspirations.

Hands measuring an architectural model with precision

Understanding the Modern Investor

Modern investors have access to more information, more products and more international opportunities than previous generations. That greater choice creates a need for stronger filtering rather than more activity. Objectives, constraints and decision rules should come before product selection.

A useful strategy therefore begins with the investor’s real circumstances: liquidity requirements, future liabilities, investment horizon, risk tolerance, family priorities, existing concentrated positions and the jurisdictions that affect ownership or access.

Why Tailoring Matters

A tailored portfolio is not simply a standard model with a different risk label. Asset allocation, banking structure, implementation method and review frequency should reflect the investor’s particular goals and the trade-offs they are willing to accept.

Two investors with the same wealth can require very different portfolios if one needs regular liquidity and capital preservation while the other has a long horizon, business income and a willingness to accept illiquidity in pursuit of growth.

Adapting to Changing Market Conditions

A strategy needs enough flexibility to respond when market conditions, interest rates, valuations or the investor’s circumstances change. Adaptation should be governed by a framework rather than short-term reactions to headlines.

Regular reviews can test whether the original assumptions remain valid, whether exposures have drifted beyond agreed limits and whether new opportunities genuinely improve the portfolio rather than simply adding complexity.

Technology and Better Decision-Making

Technology can improve reporting, aggregation and access to information, but it does not replace judgement. The most useful tools give investors a clearer view of exposures, costs, performance and risk across multiple accounts or institutions.

Used well, data supports more informed conversations between client and adviser. Used poorly, constant information can encourage unnecessary activity. The objective is clarity and discipline, not a larger volume of signals.

A Long-Term Advisory Relationship

Tailoring is an ongoing process. As careers, businesses, families and jurisdictions evolve, a suitable strategy should evolve with them. Governance, documentation and regular review are what turn a customised portfolio from a one-off recommendation into a durable wealth-management process.

Portfolio Implementation and Oversight

Once a strategy has been designed, implementation matters. The choice of banks, custodians, funds, securities and managers should support the agreed asset allocation without introducing unnecessary duplication or hidden concentration.

Consolidated reporting is particularly useful where assets are spread across institutions. It allows the investor and adviser to assess the full position, compare actual exposures with targets and identify costs or risks that are difficult to see account by account.

Transparency, Reviews and Accountability

A tailored strategy should be explainable. Clients should understand why each major allocation exists, what would cause it to change and how progress will be measured. Regular review meetings create accountability for both the portfolio and the advisory process.

Personalisation is therefore not only about product choice. It is a governance framework that connects objectives, implementation, reporting and decision-making over time.

Source

Editorial subject and source structure verified against Hexagone Group. This mockup uses original editorial wording while preserving the source topic, structure and substantive points.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.
Important Information

This article provides general information only. It does not constitute legal, investment, insurance, lending, residency, citizenship, real estate, or other professional advice. Availability and suitability depend on jurisdiction, client circumstances, and provider requirements.

Advisory Portfolio Guidance

Protecting Wealth Amid Market Volatility

Safeguarding your financial future requires a proactive and strategic approach.

New York Stock Exchange facade on Wall Street

Volatility Is a Portfolio Test, Not a Forecasting Contest

Market volatility is unavoidable. The objective of wealth protection is not to predict every decline, but to build a portfolio that can absorb adverse periods without forcing decisions that undermine long-term objectives.

That starts with understanding what must remain liquid, what can fluctuate, what losses are tolerable and which future commitments cannot depend on favourable market conditions.

Diversification and Concentration Risk

Diversification across asset classes, geographies, currencies and return drivers can reduce dependence on a single source of performance. It does not eliminate losses, but it can prevent one market shock from determining the outcome of the entire portfolio.

Concentrated company shares, a single property market or one banking relationship can create hidden risk even when the overall asset value appears substantial. Mapping concentration is therefore a core part of downside planning.

Liquidity as a Defensive Asset

Cash and high-quality liquid assets can provide optionality during periods of stress. They help meet spending or capital calls without selling long-term holdings at unfavourable prices.

The appropriate reserve depends on the client’s commitments and the liquidity profile of the rest of the portfolio. Excess cash can create an opportunity cost, while insufficient liquidity can turn temporary market volatility into a permanent loss.

Rebalancing and Risk Controls

Pre-agreed rebalancing bands can create a disciplined response to market movements. Instead of reacting emotionally, the portfolio is reviewed against target exposures and adjusted where deviations become material.

Other controls may include position limits, currency management, staged deployment and careful use of defensive or alternative strategies. Each tool should have a clear purpose and understood downside.

Maintaining a Long-Term Perspective

Periods of volatility often produce the strongest pressure to abandon a plan. A documented investment framework helps distinguish between a genuine change in fundamentals and a temporary change in market price.

Protection therefore combines portfolio construction with behaviour: sufficient liquidity, diversified exposures, realistic return expectations and a review process that allows measured action when conditions change.

Alternative Investments and Different Return Drivers

Selected alternative strategies may provide return drivers that differ from traditional public markets. Depending on structure, these can include hedge funds, private credit, private equity, real estate or commodities. The important point is not that alternatives are automatically defensive, but that their risks and liquidity can differ from listed equities and bonds.

Any allocation should therefore be assessed for manager risk, valuation, leverage, lock-ups and the possibility that diversification benefits weaken in a broad crisis. Alternatives can complement a resilient portfolio only when their role is understood and position sizes remain appropriate.

Communication and Decision Discipline

Volatile periods create behavioural pressure. A regular review process helps separate changes in the investor’s objectives from changes in market prices. Rebalancing, holding cash or changing risk should be based on the plan rather than the emotional intensity of a market move.

Clear reporting and adviser communication can also reduce the temptation to react to incomplete information. The objective is to remain capable of acting when circumstances genuinely change while avoiding unnecessary disruption to a sound long-term strategy.

Source

Editorial subject and source structure verified against Hexagone Group. This mockup uses original editorial wording while preserving the source topic, structure and substantive points.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.
Important Information

This article provides general information only. It does not constitute legal, investment, insurance, lending, residency, citizenship, real estate, or other professional advice. Availability and suitability depend on jurisdiction, client circumstances, and provider requirements.

Properties Portfolio

Building a Diversified Real Estate Portfolio

Diversification helps mitigate risk, enhance returns, and support long-term goals.

Aerial cityscape combining residential and commercial property types

Why Diversify Real Estate Exposure

Real estate can provide income, potential capital appreciation and a return pattern that differs from listed financial assets. It also carries concentration, financing, liquidity and local-market risk, so the way property exposure is spread matters.

Diversification can be approached across geography, property type, tenant profile, development stage and investment vehicle. The objective is to avoid making the portfolio dependent on one city, one sector or one economic driver.

Property Types and Economic Drivers

Residential, office, logistics, hospitality, retail and specialist property respond to different demand drivers. A portfolio that combines segments can reduce dependence on a single cycle, although correlations can rise in broad economic downturns.

Investors should consider lease duration, tenant quality, operating costs, supply pipelines and sensitivity to interest rates when comparing assets.

Direct Property, Funds and Listed Vehicles

Direct ownership offers control but requires significant capital, local expertise and active management. Funds can provide professional management and diversification, while listed REITs offer liquidity but can behave more like public equities in stressed markets.

Private real-estate vehicles sit between these approaches, often providing access to specialist strategies at the cost of longer lock-ups and more complex valuation.

Geographic Diversification

International property exposure can broaden the opportunity set, but it also introduces currency, legal, financing and management considerations. Local transaction costs, ownership rules and market transparency vary significantly.

A geographic allocation should therefore be based on the role each market plays rather than the appeal of a landmark location. Demographics, supply, economic activity and exit liquidity are more useful foundations.

Financing, Liquidity and Portfolio Review

Leverage can increase returns but also magnifies losses and refinancing risk. The debt maturity profile and interest-rate sensitivity of each asset should be reviewed alongside expected cash flows.

Property portfolios also need planned liquidity. Capital calls, maintenance and periods without tenants can create cash needs, while sales can take time. Ongoing review should consider valuation, income quality, financing and concentration together.

Investment Methods and Structures

Diversification can also be achieved through the ownership structure. Direct property offers control but concentrates operational responsibility. REITs provide liquid market exposure; private funds and partnerships can access larger or specialist assets; and co-investment structures can create targeted exposure with shared expertise.

Each method changes liquidity, governance, fees and valuation. Combining structures can be useful, but only if the investor understands how the exposures overlap and whether the portfolio remains genuinely diversified.

Market Data and Professional Review

Property decisions should be grounded in supply and demand, vacancy, rental growth, financing conditions, demographic trends and local regulation. Headline price appreciation alone provides an incomplete picture of expected return.

A periodic review can test whether the original property thesis remains valid and whether a market or asset type has grown into an unintended concentration. Rebalancing may involve new purchases, refinancing, disposals or simply directing new capital toward underrepresented segments.

Source

Editorial subject and source structure verified against Hexagone Group. This mockup uses original editorial wording while preserving the source topic, structure and substantive points.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.
Important Information

This article provides general information only. It does not constitute legal, investment, insurance, lending, residency, citizenship, real estate, or other professional advice. Availability and suitability depend on jurisdiction, client circumstances, and provider requirements.

Properties Portfolio

Incorporating Sustainable Properties in Your Portfolio

Green and energy-efficient properties can offer long-term cost savings and resilience.

Eco-friendly building with integrated green roofing

What Makes a Property Sustainable

Sustainable property goes beyond adding visible green features. Energy performance, water use, materials, transport access, resilience, indoor environmental quality and the ability to adapt over time all influence the building’s environmental footprint.

Certification systems can help create a common language, but they should complement asset-level due diligence rather than replace it.

Investment Case and Demand

Efficient buildings can benefit from lower operating costs, stronger tenant demand and better positioning as occupiers and regulators place more emphasis on energy use and emissions. These benefits are asset- and market-specific rather than automatic.

Investors should distinguish between genuinely efficient properties and assets marketed with broad sustainability claims that are not supported by measurable performance.

Regulation and Obsolescence Risk

Building standards are evolving. Assets that require substantial retrofitting to meet future efficiency requirements may face higher capital expenditure or weaker liquidity.

This creates a form of obsolescence risk: a property can remain physically usable while becoming less competitive economically because its energy performance, systems or design no longer meet tenant or regulatory expectations.

Ways to Gain Exposure

Sustainable real estate can be accessed through direct property, development projects, private funds or listed vehicles. Each approach has different levels of liquidity, diversification, control and implementation cost.

The chosen structure should fit the investor’s wider property allocation and avoid concentrating sustainability exposure in a single project or market.

Due Diligence and Monitoring

A useful review considers actual energy data, certification status, retrofit requirements, tenant profile, location resilience and management capability. For development projects, construction standards and delivery risk are equally important.

Sustainability should ultimately be integrated into conventional investment analysis: price, cash flow, financing, risk and exit assumptions remain decisive.

Certifications, Location and Community Context

Recognised frameworks such as LEED, BREEAM and WELL can help organise due diligence, but certification should be considered alongside actual operating data. Transport access, local planning policy, resilience and the relationship between a building and its surrounding community also affect long-term demand.

A sustainable building in a weak location can still be a poor investment, while an older asset with a credible retrofit plan may offer attractive improvement potential. Sustainability metrics therefore sit within—not outside—the conventional property-investment case.

Financing and Retrofit Economics

Green lending or other financing incentives may improve project economics in some markets, while retrofit requirements can create significant future capital expenditure in others. Investors should model these costs rather than assuming that a sustainability label automatically produces a premium.

For existing buildings, the quality of the transition plan can be as important as current certification. Energy upgrades, building systems and tenant engagement may determine whether an asset remains competitive as standards tighten.

Source

Editorial subject and source structure verified against Hexagone Group. This mockup uses original editorial wording while preserving the source topic, structure and substantive points.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.
Important Information

This article provides general information only. It does not constitute legal, investment, insurance, lending, residency, citizenship, real estate, or other professional advice. Availability and suitability depend on jurisdiction, client circumstances, and provider requirements.

Private Wealth Advisory

Family Protection: The Cornerstone of Wealth Management

Safeguarding family ties and preserving legacies is a responsibility, not just a priority.

Intergenerational hands expressing support, protection and continuity

Protection Before Complexity

Wealth management is not only about growing assets. Families also need a plan for events that can interrupt income, decision-making or succession. Protection creates the foundation on which longer-term investment and estate strategies can operate.

The starting point is to identify the financial consequences of death, incapacity, illness, business disruption or a major change in family circumstances.

Insurance and Liquidity

Life and protection insurance can provide liquidity when a family would otherwise need to sell assets quickly. The appropriate structure depends on the liabilities being protected, the beneficiaries and the length of time the protection is needed.

Coverage should be reviewed when debts, dependants, business interests or residence change. A policy that was appropriate several years ago may no longer match the current exposure.

Estate and Succession Planning

Wills, beneficiary designations, ownership structures and governance arrangements help determine how assets are controlled and transferred. Cross-border families need particular care because more than one legal system can apply.

A coordinated plan reduces the risk that individual documents contradict one another or that assets fall outside the intended succession framework.

Family Governance and Communication

Protection is also organisational. Families benefit from clear records, defined decision-making responsibilities and a shared understanding of where essential documents and advisers can be found.

For larger or more complex families, governance can include regular family meetings, policies for shared assets and education for the next generation.

Reviewing the Protection Framework

Protection planning should be revisited after major life events and at regular intervals. The review should consider insurance, liquidity, estate documents, account ownership, beneficiaries and emergency decision-making together rather than as separate tasks.

Tailored Protection for Different Family Structures

No two families face the same mix of dependants, businesses, jurisdictions and legacy objectives. Protection planning should therefore reflect the family’s actual decision-making structure and the people who would need access to liquidity or authority during a difficult event.

For entrepreneurial families, continuity planning may also need to address ownership and control of operating businesses. For internationally mobile families, legal documents and insurance arrangements should be reviewed across jurisdictions rather than assumed to travel automatically.

Building a Lasting Legacy

A durable legacy includes more than the transfer of assets. Education, governance, philanthropy and shared family principles can influence how wealth is understood and used by future generations.

The practical aim is continuity: family members should know the purpose of the plan, the roles they may eventually assume and where to find the advisers and documents required to act. This reduces uncertainty at the moments when clarity matters most.

Source

Editorial subject and source structure verified against Hexagone Group. This mockup uses original editorial wording while preserving the source topic, structure and substantive points.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.
Important Information

This article provides general information only. It does not constitute legal, investment, insurance, lending, residency, citizenship, real estate, or other professional advice. Availability and suitability depend on jurisdiction, client circumstances, and provider requirements.

Investment Knowledge

Private Banking

Understanding private banking relationships, how they are structured, and how they complement independent advice.

Contemporary financial-district architecture

What Private Banking Is

Private banking combines banking, investment access, financing and relationship management for clients whose assets and financial affairs require more coordination than a standard retail-banking relationship. The quality of the service depends on the institution, booking centre, adviser model and the range of services actually available to the client.

A private bank can provide custody, deposits, lending, investment products and portfolio services. It may also coordinate with external advisers on legal, estate or cross-border matters, although the regulatory scope varies by jurisdiction.

Define the Role of the Bank

Before selecting an institution, decide what the bank is expected to do. Some clients primarily need a secure custody and execution platform. Others need lending against assets, discretionary management, access to private markets or a relationship that can operate across several countries.

The clearer the mandate, the easier it becomes to compare institutions on relevant criteria rather than brand recognition alone.

Core Selection Criteria

A structured review should examine regulatory status, balance-sheet strength, custody arrangements, service model, platform breadth, lending capability, pricing, digital access and geographic reach. Minimum asset requirements and product eligibility can also differ significantly.

The relationship manager matters, but the institution behind that person matters more. Clients should understand how advice is produced, how conflicts are managed and what happens if the relationship manager changes.

Open Architecture and Product Access

Some banks emphasise proprietary products; others operate a more open architecture. Neither model is automatically superior, but the client should know whether recommendations are drawn from the wider market and how product-selection incentives are structured.

For complex portfolios, access to third-party funds, ETFs, direct securities, structured products and private markets can affect how efficiently the overall strategy is implemented.

Fees, Conflicts and Transparency

Private-banking costs can include custody, advisory, discretionary-management, transaction, foreign-exchange, product and financing charges. Comparing headline fees alone can therefore be misleading.

A useful review looks at the total economic cost and asks how the bank and adviser are compensated. Transparent reporting helps the client understand whether the service being received justifies the full cost.

Single Bank or Multi-Bank Structure

Using more than one bank can diversify counterparty exposure and broaden access, but it also creates complexity. Consolidated reporting and a clear allocation of roles can prevent duplication and conflicting recommendations.

A multi-bank arrangement is most effective when each institution has a defined purpose and the client has a way to view the combined portfolio rather than managing each account in isolation.

Ongoing Oversight

Bank selection is not a one-time decision. Service quality, personnel, product access, pricing and the institution’s strategic focus can change. Periodic benchmarking keeps the relationship aligned with the client’s needs.

Questions to Ask Before Opening a Relationship

Ask where assets will be booked and custodied, what legal entity will hold the relationship, which services are regulated in that jurisdiction, and whether the bank can continue serving you after a move. Clarify who provides investment advice and whether that person can recommend third-party products.

Request a complete schedule of custody, advisory, management, transaction, foreign-exchange, credit and product charges. Ask how conflicts of interest are disclosed and how the bank handles complaints, adviser changes and service escalation.

A Practical Bank-Selection Scorecard

A useful comparison can score institutions across safety and regulation, investment platform, financing, international portability, service quality, digital capability, reporting and total cost. Weight the categories according to the role you expect the bank to play rather than giving every factor equal importance.

The strongest brand is not automatically the strongest fit. A smaller booking centre with better access, service and product architecture may be more useful than a larger institution whose operating model does not match the client’s needs.

Review Checklist

Review the relationship at least periodically: service quality, pricing, lending terms, product access, portfolio reporting, counterparty concentration and the suitability of the booking centre. A change of residence, liquidity need or family structure is also a natural trigger for review.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.

Important Information

General information only. Not legal, investment, insurance, tax, or other professional advice. Availability and suitability depend on jurisdiction and individual circumstances.

Investment Knowledge

Offshore & International Banking

How international account structures work across jurisdictions, and the questions to ask before opening one.

International urban banking and financial architecture

What International Banking Means

International banking refers to holding banking or investment relationships outside a client’s country of residence or across multiple financial centres. It can support mobility, currency diversification, international investing and the practical administration of assets held in more than one jurisdiction.

The objective should be functional rather than simply geographic. A cross-border account needs to solve a defined problem—such as custody, currency management, access or portability—while remaining fully compliant with applicable reporting and regulatory requirements.

Choosing the Jurisdiction and Institution

Jurisdiction selection should consider regulatory standards, political and legal stability, deposit or custody protections, currency infrastructure, account portability and the bank’s ability to service the client after a change of residence.

Institution-level due diligence remains essential. A strong jurisdiction does not remove bank-specific credit, service or operational risk.

Currency and Liquidity Management

International families often hold liabilities in more than one currency. Banking arrangements can help match liquid assets to expected spending and reduce the need for forced currency conversion at unfavourable times.

Currency diversification is not the same as eliminating currency risk. Exposures should be measured across accounts and investments so that unintentional concentration does not build up.

Cross-Border Access and Portability

A relationship that works in one country may not be available after relocation. Product permissions, documentation and tax reporting can change when residency changes.

Clients should therefore ask how the bank handles international moves, whether the booking centre can continue servicing them, and what restrictions may apply to investments or credit facilities.

Compliance and Documentation

International banking involves enhanced documentation. Banks may require evidence of identity, residence, source of wealth, source of funds and the purpose of the relationship. These requirements are part of the regulated onboarding process.

Accurate records and timely updates reduce friction when circumstances change. International structures should also be reviewed with qualified legal or tax advisers where necessary.

Managing Multiple Relationships

Where several institutions are used, consolidated oversight becomes important. The family should understand total cash, credit, currency, investment and counterparty exposure rather than relying on separate bank statements.

Operational Risks and Practical Controls

Cross-border banking introduces operational considerations such as payment cut-off times, correspondent-bank chains, currency conversion, documentation expiry and differences in digital authentication. These can matter as much as investment access when funds need to move quickly.

Maintaining current contact details, tax-residency declarations and source-of-funds records can reduce delays. Families should also know which trusted persons can act if the primary account holder is unavailable.

Banking Architecture for International Families

A simple architecture often works better than a collection of unrelated accounts. One relationship may serve as the operating-liquidity bank, another as the principal custody and investment platform, while a third may provide specialist financing or geographic access.

Defining the purpose of each relationship helps avoid duplicated cash balances, inconsistent portfolios and unnecessary costs.

Review Checklist

Confirm regulatory status, booking centre, custody arrangements, currencies, service after relocation, total fees, credit exposure, emergency access and the reporting available across institutions. Reassess the structure whenever residency or major asset locations change.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.

Important Information

General information only. Not legal, investment, insurance, tax, or other professional advice. Availability and suitability depend on jurisdiction and individual circumstances.

Investment Knowledge

Structured Products & Notes

What structured products are, how payoffs are built, and where they can fit within a portfolio.

Close architectural study of a structured bridge system

How Structured Products Work

Structured products combine a conventional instrument, often a bond or deposit-like component, with derivatives that determine the payoff. The result can be engineered for capital protection, enhanced income, conditional yield or participation in an underlying market.

The payoff is defined in advance and may depend on barriers, caps, observation dates or the performance of one or more reference assets. Investors should understand the formula before considering the headline coupon or participation rate.

Structured Notes and Issuer Risk

A structured note is typically an unsecured obligation of the issuing bank. Even when the payoff contains a protection feature, the investor remains exposed to the creditworthiness of the issuer.

This distinction is crucial: product-level protection does not eliminate issuer default risk. Diversifying issuers and understanding the legal form of the instrument are part of proper risk assessment.

Common Structures

Capital-protected notes seek to return some or all principal at maturity while providing limited participation in upside. Yield-enhancement structures exchange additional income for conditional downside exposure. Autocallables may redeem early when predefined conditions are met. Participation notes provide targeted exposure, sometimes with caps or leverage.

Each structure solves a different portfolio problem and carries a different worst-case outcome. Products should be compared on payoff mechanics, not labels.

Barriers, Observation Dates and Path Dependency

Many products depend not only on where an underlying finishes but on what happens during the life of the investment. A barrier breach or observation-date condition can materially change the final payoff.

Scenario analysis should therefore include adverse paths, not just central forecasts. Investors should know the loss profile if the underlying falls sharply, remains below a barrier or recovers only after a critical observation date.

Liquidity, Valuation and Costs

Structured products are commonly designed to be held to maturity. Secondary-market liquidity can be limited and the issuer may be the main source of a bid, creating potential discounts for early exit.

Costs may be embedded in the issuance price rather than displayed as a simple fee. Comparing the product with the cost of its underlying components can help assess value.

Suitability and Portfolio Use

Structured products can be useful when their payoff addresses a specific portfolio objective and the investor can tolerate the relevant risks. They should not be selected solely because a coupon looks attractive.

Position size, issuer concentration, liquidity needs and the relationship between the structured payoff and the rest of the portfolio should all be considered.

Sources

Official Hexagone Group Investment Knowledge: Understanding Structured Products and Structured Notes Explained. The Investment Knowledge articles also reference DFSA conduct standards and financial-stability material on derivatives markets.

Scenario Analysis Before Investment

Before investing, model the payoff under several paths: a strong rise, a flat market, a moderate fall, a barrier breach and an issuer-credit event. For autocallables, consider what happens at each observation date rather than only at final maturity.

This exercise makes the trade-offs visible. High coupons may be compensation for accepting equity downside, capped upside, path dependency or limited liquidity.

Documentation and Key Terms

The term sheet and final legal documents govern the investment. Key terms include issuer, currency, maturity, underlying assets, initial levels, barriers, coupon conditions, observation dates, redemption formula and any call features.

Investors should also understand whether the product is secured or unsecured, whether there is a secondary market and how valuations will be provided during the life of the instrument.

Review Checklist

Confirm the objective, worst-case loss, issuer exposure, liquidity horizon, payoff formula, embedded costs, tax/legal treatment where relevant, and how the position interacts with other structured products or the same underlying assets already held in the portfolio.

Source

Editorial subject and source structure verified against Hexagone Group. This mockup uses original editorial wording while preserving the source topic, structure and substantive points.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.

Important Information

General information only. Not legal, investment, insurance, tax, or other professional advice. Availability and suitability depend on jurisdiction and individual circumstances.

Investment Knowledge

Estate Planning & Wealth Transfer

International wills, succession, and passing wealth between generations with clarity and control.

Classical columns and durable architectural structure

Estate Planning in an International Context

Estate planning coordinates how assets are owned, controlled and transferred during life and after death. International families face additional complexity because wills, inheritance rules and taxes can differ across the jurisdictions connected to the family or its assets.

A robust plan begins with an inventory of assets, ownership structures, beneficiaries and the legal systems that may apply. The objective is to reduce uncertainty and ensure that separate documents work together.

Wills and Succession Documents

A will that is valid in one jurisdiction may not automatically control assets elsewhere. Families with material assets in several countries often need local legal advice and, in some cases, coordinated jurisdiction-specific wills.

Beneficiary designations on insurance, pensions and financial accounts should be checked alongside wills so that transfer instructions do not conflict.

Lifetime Gifting and Inheritance

Wealth can be transferred during life or at death. Lifetime gifting may allow gradual transfer and education of the next generation, while inheritance can preserve control for longer. Each route has legal, tax, liquidity and family-governance implications.

The timing and form of transfer should be chosen deliberately rather than driven only by tax considerations.

Trusts and Other Wealth Structures

Trusts can separate legal ownership, beneficial enjoyment and control, making them useful for succession, protection and governance in appropriate jurisdictions. Other structures may include foundations, holding companies or family partnerships.

The right vehicle depends on residence, citizenship, asset location, family circumstances and regulatory requirements. Cross-border structures require specialist legal and tax advice.

Cross-Border Risks

Forced-heirship rules, conflicting succession laws and the possibility of more than one country taxing the same estate can create significant complexity. Relocation can also change which laws or taxes apply.

Plans should be reviewed whenever residence, marriage, family structure, business ownership or the location of significant assets changes.

UAE and DIFC Considerations

For internationally mobile families connected to the UAE, DIFC or ADGM wills may form part of the planning framework for eligible non-Muslim individuals and relevant UAE assets. The appropriate solution depends on the person’s circumstances and should be coordinated with advice in other jurisdictions.

Governance and Family Communication

A technically correct structure can still fail if family members do not understand roles, responsibilities or the purpose of the plan. Governance, document organisation and communication are therefore practical parts of wealth transfer.

Source Framework

This Investment Knowledge article is based on Hexagone Group’s internal Investment Knowledge material on estate planning, wealth structuring, international wills, generational wealth and wealth-transfer strategies, together with the current Investment Knowledge pages on international estate planning and wealth transfer.

Building the Estate Inventory

The planning process begins with a complete inventory of real property, investment accounts, business interests, insurance, pensions, digital assets and significant personal assets. Record legal ownership, location, approximate value, beneficiaries and any debt attached to the asset.

This inventory reveals which jurisdictions and legal documents need to be coordinated and helps identify assets that may pass outside a will.

Incapacity and Decision-Making

Estate planning should also address incapacity, not only death. Powers of attorney, guardianship arrangements and corporate-authority documents can determine who is able to act when the owner cannot.

For business owners, succession of management and voting control may require separate shareholder or governance arrangements in addition to personal estate documents.

Review Checklist

Review wills, beneficiary nominations, ownership structures, trusts or foundations, insurance, powers of attorney, business succession and document storage. Revisit the plan after relocation, marriage or divorce, births, deaths, major asset purchases or a business sale.

Source

Editorial subject and source structure verified against Hexagone Group. This mockup uses original editorial wording while preserving the source topic, structure and substantive points.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.

Important Information

General information only. Not legal, investment, insurance, tax, or other professional advice. Availability and suitability depend on jurisdiction and individual circumstances.

Investment Knowledge

Alternative Investments

A plain-language look at private equity, private credit, and hedge-fund strategies, and the discipline they require.

Modern infrastructure and specialist engineering structure

Understanding the Alternative Investment Universe

Alternative investments cover strategies and assets outside conventional long-only public equities and investment-grade bonds. They can include hedge funds, private equity, private credit, real assets and structured solutions.

The category is broad, so the label itself says little about risk. Each strategy needs to be understood on its own terms: return driver, liquidity, leverage, valuation, fees and dependence on manager skill.

Hedge Funds

Hedge funds may use long/short positioning, derivatives, relative-value trades, event-driven strategies or macro exposures. Their portfolio role can include diversification or downside management, but outcomes vary substantially between managers.

Due diligence should examine investment process, risk controls, liquidity terms, leverage, operational infrastructure and historical behaviour in stressed markets.

Private Equity

Private equity provides capital to privately held companies through buyouts, growth strategies or venture investment. Returns depend on business performance, entry valuation, operational improvement and the eventual exit environment.

Capital is normally committed for many years and cash flows are irregular. Vintage diversification and manager selection are therefore important.

Private Credit

Private credit funds lend outside traditional public bond markets. Strategies can range from senior secured direct lending to mezzanine, distressed and specialist finance.

The potential return includes compensation for illiquidity and complexity, but underwriting quality, borrower leverage, covenant protection and recovery prospects matter greatly.

Real Assets and Specialist Strategies

Infrastructure, property, commodities and other real assets can provide exposure to long-duration cash flows or tangible assets. Their sensitivity to inflation, regulation, financing and economic cycles varies by strategy.

Specialist strategies should be assessed for concentration and for the operational expertise required to manage the underlying assets.

Liquidity, Valuation and Fees

Alternatives often involve lock-ups, notice periods or capital-call structures. Valuations may be periodic rather than continuously observable, and layered fees can materially affect net returns.

The portfolio should maintain enough liquid assets to meet commitments without relying on a sale of illiquid positions.

Portfolio Construction

Alternatives are most useful when each allocation has a defined role—return enhancement, diversification, income, inflation sensitivity or access to a specific opportunity set. Aggregating exposures across managers helps reveal hidden concentration and leverage.

Source Framework

Official Hexagone Group Investment Knowledge: Alternative Investment Funds Explained, together with dedicated Hexagone material on hedge funds, private equity, private credit and structured products.

Manager and Operational Due Diligence

For manager-led strategies, investment performance is only part of due diligence. Governance, valuation policy, service providers, custody, cybersecurity, conflicts, key-person risk and the manager’s own financial stability can all influence the outcome.

Private funds also require close review of legal terms: capital calls, distributions, recycling, extensions, transfer restrictions and the circumstances under which an investor can exit.

Cash-Flow Planning for Illiquid Assets

Private equity and private credit commitments may draw capital over time rather than on day one. Investors therefore need a liquidity plan for future calls and should not assume that distributions will arrive on a predictable schedule.

Commitment pacing across vintages can help smooth cash flows and reduce the risk of concentrating capital in a single market environment.

Review Checklist

For each alternative allocation, document the portfolio role, liquidity terms, expected return driver, leverage, valuation method, fees, manager risks and the maximum exposure you are prepared to hold. Review aggregate illiquidity across all funds rather than one commitment at a time.

Source

Editorial subject and source structure verified against Hexagone Group. This mockup uses original editorial wording while preserving the source topic, structure and substantive points.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.

Important Information

General information only. Not legal, investment, insurance, tax, or other professional advice. Availability and suitability depend on jurisdiction and individual circumstances.

Investment Knowledge

Life Insurance Structures

Term, whole, universal, and private-placement life insurance, and the role each can play in a plan.

Layered library interior suggesting continuity and structured planning

Life Insurance as Protection and Structure

Life insurance can serve a straightforward protection need or form part of a broader cross-border wealth structure. The role of the policy depends on its type, jurisdiction, investment features and ownership arrangement.

The starting point is always the objective: replacing income, providing estate liquidity, protecting dependants, holding investments inside an insurance wrapper or supporting intergenerational transfer.

Term Life Insurance

Term insurance provides a defined death benefit for a specified period. It is generally used where the need for protection is time-limited, such as during working years, while liabilities are outstanding or while dependants rely on income.

Because it is primarily protection rather than investment, it is usually simpler than permanent or investment-linked policies.

European Life Insurance

European life-insurance structures, particularly those used in Luxembourg and other cross-border centres, can combine insurance with investment and wealth-planning features. Unit-linked and dedicated-fund structures may offer access to a broad investment universe subject to local rules.

Regulatory protections, insurer quality, custody and the client’s jurisdiction all need to be assessed together.

International and Offshore Life Insurance

International policies are designed for clients whose residence, assets or family connections cross borders. Portability can be valuable, but the treatment of a policy may change when the policyholder moves.

Policy domicile, ownership, beneficiary provisions, surrender terms and reporting obligations should therefore be reviewed before and after relocation.

Private Placement Life Insurance

PPLI is a bespoke insurance wrapper used by qualifying high-net-worth clients to hold an investment portfolio within a life-insurance contract. Its advantages and restrictions depend heavily on jurisdiction and on maintaining the legal characteristics of insurance.

Asset eligibility, investment control, policy charges and tax treatment require specialist review. It should not be treated as a generic tax product.

Universal Life Structures

Universal life policies can combine a death benefit with a cash-value component. Index universal life links credited interest to a market index under defined formulas, while variable universal life allows investment in selected sub-accounts and therefore carries direct investment risk.

Illustrations depend on assumptions and should be stress-tested rather than treated as guarantees.

Due Diligence and Ongoing Review

Before establishing a policy, review insurer strength, jurisdiction, fees, surrender provisions, beneficiary arrangements, investment options and the consequences of changing residence. Policies should be revisited as family circumstances and regulation evolve.

Source Framework

Official Hexagone Group Investment Knowledge: International Life Insurance, European Life Insurance and Term Life Insurance, together with Hexagone’s educational material on PPLI and universal-life structures.

Ownership, Beneficiaries and Estate Coordination

Policy ownership and beneficiary designations can be as important as the policy type. The arrangement should be coordinated with wills, trusts and other estate documents so that the intended transfer route is clear.

Changes in marriage, dependants, residence or business ownership can make older nominations inappropriate, so periodic beneficiary review is essential.

Fees, Illustrations and Surrender Terms

Permanent and investment-linked policies can contain multiple charges: insurance cost, administration, asset management, fund expenses and surrender charges. These should be understood in aggregate rather than evaluated one line at a time.

Illustrations are scenarios based on assumptions. Review guaranteed and non-guaranteed elements separately, and stress-test lower investment returns or higher insurance costs where relevant.

Review Checklist

Confirm policy objective, insurer, jurisdiction, currency, owner, insured life, beneficiaries, death benefit, cash-value mechanics, investment options, total charges, surrender conditions and portability. Reassess after relocation or a material change in family circumstances.

Source

Editorial subject and source structure verified against Hexagone Group. This mockup uses original editorial wording while preserving the source topic, structure and substantive points.

Important notice: This material is provided for educational purposes only and does not constitute investment, legal or tax advice. Investment values can fall as well as rise, and suitability depends on individual circumstances.

Important Information

General information only. Not legal, investment, insurance, tax, or other professional advice. Availability and suitability depend on jurisdiction and individual circumstances.

Careers

Build your career where judgement matters.

Hexagone Group welcomes people who combine ambition with discipline, curiosity with responsibility, and strong interpersonal judgement with a commitment to high standards.

View Open Roles↓
HEXAGONE GROUP DUBAI
A place to learn, contribute, and take responsibility

High standards, real responsibility, international perspective.

Our work sits at the intersection of finance, client service, international coordination, and long term planning. Team members are expected to think carefully, communicate clearly, and understand how their contribution affects the client experience.

We value established academic and professional backgrounds, but we also recognise the strength of less conventional profiles. Character, discipline, judgement, and the ability to learn remain central to every role.

International Perspective

Work across markets, cultures, and client situations that require thoughtful coordination.

Meaningful Responsibility

Contribute to real work from the outset, with clear expectations, support, and accountability.

High Standards

Learn to approach research, documentation, communication, and service with precision.

Continued Development

Build technical knowledge, professional judgement, and the confidence to take on wider responsibility.

Damien Soler, Partner and Head of Human Division
Damien SolerPartner and Head of Human Division
People & Culture

Building teams for the long term

At Hexagone Group, building the right team is approached with the same care as building long-term client relationships. We look for people who combine professional standards, curiosity, judgement and the ability to work across cultures.

A leadership perspective

We look for people who are serious about their work, open to learning, and comfortable taking responsibility. The aim is to build teams that can grow with the firm over the long term.

Inside Hexagone Group

Experience our workplace and culture.

Hear directly from our team and take a closer look at the environment, standards, and opportunities that shape a career at Hexagone Group.

Hexagone Capital Dubai office environmentHEXAGONE GROUP DUBAI
Open positions

Current opportunities.

Role availability may change as hiring needs evolve. Current opportunities are shown below.

Apply to Hexagone Group

Submit your profile.

Complete the form and include the information relevant to the role. The recruitment team will review your application and respond if your profile is selected for the next stage.

Role
Career opportunity

Elite Internship Opportunity

This page provides the application route for this opportunity. Role scope, location, working arrangements, and experience requirements are discussed during the recruitment process.

Apply Now→
Location

Discussed during recruitment

Department

Hexagone Group

Employment type

Discussed during recruitment

Status

Application route available

Recruitment note

Applicant information is handled for recruitment purposes in accordance with the Privacy Policy and applicable recruitment processes.

Career opportunity

Graduate Leadership Program in Business Development

This page provides the application route for this opportunity. Role scope, location, working arrangements, and experience requirements are discussed during the recruitment process.

Apply Now→
Location

Discussed during recruitment

Department

Hexagone Group

Employment type

Discussed during recruitment

Status

Application route available

Recruitment note

Applicant information is handled for recruitment purposes in accordance with the Privacy Policy and applicable recruitment processes.

Career opportunity

Wealth Management Associate

This page provides the application route for this opportunity. Role scope, location, working arrangements, and experience requirements are discussed during the recruitment process.

Apply Now→
Location

Discussed during recruitment

Department

Hexagone Group

Employment type

Discussed during recruitment

Status

Application route available

Recruitment note

Applicant information is handled for recruitment purposes in accordance with the Privacy Policy and applicable recruitment processes.

Career opportunity

Wealth Adviser

This page provides the application route for this opportunity. Role scope, location, working arrangements, and experience requirements are discussed during the recruitment process.

Apply Now→
Location

Discussed during recruitment

Department

Hexagone Group

Employment type

Discussed during recruitment

Status

Application route available

Recruitment note

Applicant information is handled for recruitment purposes in accordance with the Privacy Policy and applicable recruitment processes.

Contact

A clear route to the right team.

Choose the enquiry type and legal entity or jurisdiction that best match your request. Your information will be directed to the appropriate Hexagone Group contact or affiliated entity.

A structured review

Three details help us direct your enquiry properly.

01

Location

Tell us where you are based or the jurisdiction most relevant to your request.

02

Principal need

Identify the main reason for your enquiry so the right team can review it.

03

Relevant entity

Select the Hexagone entity or route that may be responsible for the engagement.

Send an enquiry

Begin Your Journey With Us.

Provide the details below so your enquiry can be directed appropriately. Please do not submit passwords, account credentials, or highly sensitive personal documents through this form.

01
RegionIdentifies the geographic route most relevant to your request.
02
NeedHelps distinguish advisory, business, media, careers, or general enquiries.
03
EntityConfirms the appropriate legal entity before any regulated engagement.
Your enquiry contextWe will retain the context of the page you came from.
Initial enquiry routeSelect a region to see the relevant Hexagone route.

The legal entity and service scope will be identified before any regulated engagement.

Enquiry contacts

Direct routes for specific requests.

Region

Africa

A regional starting point for enquiries connected to African markets.

International access

Start with geography, then follow the appropriate Hexagone route.

Hexagone Group serves an international audience through separate legal entities and professional relationships. The relevant route depends on jurisdiction, the nature of the enquiry, and the applicable scope of activity.

Regional enquiries

Begin with the central Hexagone Group contact route.

Share your location and area of interest so the enquiry can be directed appropriately. This page does not imply a local Hexagone office, branch, regulated entity, or licence.

Begin a regional enquiry→
Region

East Asia

Regional access for enquiries connected to East Asia.

International access

Start with geography, then follow the appropriate Hexagone route.

Hexagone Group serves an international audience through separate legal entities and professional relationships. The relevant route depends on jurisdiction, the nature of the enquiry, and the applicable scope of activity.

Region

Europe

Regional access for enquiries connected to Europe.

International access

Start with geography, then follow the appropriate Hexagone route.

Hexagone Group serves an international audience through separate legal entities and professional relationships. The relevant route depends on jurisdiction, the nature of the enquiry, and the applicable scope of activity.

Region

Middle East

Regional access for enquiries connected to the Middle East.

International access

Start with geography, then follow the appropriate Hexagone route.

Hexagone Group serves an international audience through separate legal entities and professional relationships. The relevant route depends on jurisdiction, the nature of the enquiry, and the applicable scope of activity.

Region

Other International Market

A central route for international markets not covered by a named regional destination.

International access

Start with geography, then follow the appropriate Hexagone route.

Hexagone Group serves an international audience through separate legal entities and professional relationships. The relevant route depends on jurisdiction, the nature of the enquiry, and the applicable scope of activity.

Regional enquiries

Begin with the central Hexagone Group contact route.

Share your location and area of interest so the enquiry can be directed appropriately. This page does not imply a local Hexagone office, branch, regulated entity, or licence.

Begin a regional enquiry→
Region

South America

A regional starting point for enquiries connected to South American markets.

International access

Start with geography, then follow the appropriate Hexagone route.

Hexagone Group serves an international audience through separate legal entities and professional relationships. The relevant route depends on jurisdiction, the nature of the enquiry, and the applicable scope of activity.

Regional enquiries

Begin with the central Hexagone Group contact route.

Share your location and area of interest so the enquiry can be directed appropriately. This page does not imply a local Hexagone office, branch, regulated entity, or licence.

Begin a regional enquiry→
Region

Southeast Asia

Regional access for enquiries connected to Southeast Asia.

International access

Start with geography, then follow the appropriate Hexagone route.

Hexagone Group serves an international audience through separate legal entities and professional relationships. The relevant route depends on jurisdiction, the nature of the enquiry, and the applicable scope of activity.

Bali, Indonesia

Hexagone Group Bali

Hexagone Group subsidiary in Bali, Indonesia.

Group subsidiary

Hexagone Group Bali

Hexagone Group Bali is presented on this website as a Hexagone Group subsidiary in Bali.

LocationBali, Indonesia
PresentationHexagone Group subsidiary
AddressHouse of Kairos, Seseh Bali, Jalan Pantai Munggu Pengembungan, Bali, Indonesia
Local Leadership

Steeven Michel

Wealth Advisor

Part of Hexagone Group's leadership presence in Bali.

Start a conversation
Steeven Michel, Hexagone Group Bali
SubsidiaryHexagone Group Bali
Bali enquiries

Start a conversation with Hexagone Group.

Use the central enquiry form to share your location and the nature of your enquiry.

Start a Bali enquiry→
Malaysia

Hexagone Group Malaysia

Hexagone Group subsidiary in Malaysia.

Group subsidiary

Hexagone Group Malaysia

Hexagone Group Malaysia is presented on this website as a Hexagone Group subsidiary in Malaysia.

LocationMalaysia
PresentationHexagone Group subsidiary
David Palacci, Senior Partner at Hexagone Group
Local Leadership

David Palacci

Senior Partner

Supporting Hexagone Group's international advisory relationships and presence in Malaysia.

Start a conversation
SubsidiaryHexagone Group Malaysia
Malaysia enquiries

Start a conversation with Hexagone Group.

Use the central enquiry form to share your location and the nature of your enquiry.

Start a Malaysia enquiry→
Home/Policies/Complaint Handling Procedure
← Back to Policies Client Support

Complaint Handling Procedure

Hexagone Group is committed to receiving and addressing complaints in a clear and appropriate manner. The process applicable to a complaint may depend on the Hexagone company involved, the relevant jurisdiction and any applicable regulatory requirements.

International starting point

How complaints are handled

Complaints may be submitted in writing and will be reviewed to understand the nature of the concern, identify the relevant Hexagone company, determine the appropriate person or team to handle it, and establish whether an entity-specific regulatory procedure applies.

The applicable process may depend on the relevant Hexagone company and jurisdiction. Entity-specific legal or regulatory requirements may therefore apply.

Submitting a complaint

Information to include

Please provide enough information for the concern to be understood and directed appropriately. Where relevant, this may include:

  • Your name and contact details.
  • The relevant Hexagone company, if known.
  • A clear description of the concern.
  • Relevant dates or circumstances.
  • Supporting information where appropriate.

Please do not submit passwords, account credentials, or unnecessary sensitive personal information.

Review and routing

Directing the matter appropriately

The complaint will be reviewed and, where necessary, directed to the relevant Hexagone company or responsible contact.

Where a complaint concerns a specific Hexagone company, the matter may be handled under that company's own complaint-handling and regulatory requirements.

Response

Communication during the review

Hexagone will seek to acknowledge the complaint appropriately, review the matter, communicate with the complainant where further information is required, and provide an appropriate response once the matter has been reviewed.

Complaints will be addressed as promptly as reasonably practicable, subject to the nature of the matter and any process or regulatory requirements that apply to the relevant Hexagone company.

Records and confidentiality

Handling complaint information

Complaint information may be recorded and handled in accordance with applicable internal, legal, privacy and regulatory requirements. Personal information is handled subject to the Privacy Policy and the requirements applicable to the relevant Hexagone company.

Entity-specific complaint procedures

Separate regulatory procedures may apply

Certain Hexagone companies may be subject to separate regulatory complaint procedures. Where an entity-specific procedure applies, it should be used for complaints concerning that company.

Hexagone Capital (UAE) LimitedDubai, United Arab EmiratesView Dubai Complaint Handling Procedure
General contact

Complaint enquiries

For general complaints or where the relevant Hexagone company is not known, contact:

General Complaint Form

Submit a complaint online

Use the form to provide the information needed for Hexagone Group to understand your complaint and direct it to the appropriate company or responsible contact.

Complaint submissions are handled separately from general enquiries and marketing communications.

CONTACT REGARDING A COMPLAINT
Home/Group Entities/Hexagone Capital Dubai/Complaint Handling Procedure
← Back to Hexagone Capital Dubai Client Support

Complaint Handling Procedure

This entity-specific procedure applies to complaints concerning Hexagone Capital (UAE) Limited and sets out the Dubai complaint process, including the applicable regulatory context and escalation routes.

Hexagone Capital (UAE) Limited

Dubai complaint procedure

This procedure applies to complaints concerning Hexagone Capital (UAE) Limited and covers complaints made verbally or in writing, including how they are recorded, reviewed, resolved and retained.

Complaints are handled through Compliance and kept within the firm's formal complaints records.

Published regulatory context The current published procedure identifies the DIFC business at Unit 2803, Level 28, Al Fattan Currency House, DIFC, Dubai, UAE as regulated by the Dubai Financial Services Authority (DFSA) under a Category 4 licence, DFSA Reference Number F007596. It lists permissions to advise on financial products and arrange deals in investments.
01

Receiving and Recording the Complaint

Verbal and written complaints are recorded and sent promptly to the Compliance Officer. A verbal complaint may be requested in writing.

An employee directly involved in the complaint cannot handle its resolution.

02

Acknowledgement of the Complaint

The Compliance Officer acknowledges the complaint in writing within 7 business days and provides the procedure and expected timetable.

Where immediate resolution is possible, the outcome may be communicated the same day.

03

Investigation of the Complaint

The Compliance Officer and Senior Executive Officer investigate the complaint promptly, considering its seriousness, implications and the timetable communicated to the client.

04

Resolution of the Complaint

A formal response is provided within 30 business days, explaining the outcome, action taken and any appropriate redress.

If more investigation is required, the client is informed and given a revised timetable.

05

Recording the Outcome

The outcome and supporting records are entered in the complaints register and retained for at least 6 years.

06

Review and Mitigation

Compliance reviews relevant systems and controls after resolution and implements mitigation where needed.

07

Reporting to the Board

Complaint status is included in the quarterly compliance report to the Board of Directors.

Other regulated entities

Complaints involving another regulated institution

If another regulated institution may be responsible, the client is informed in writing and consent is obtained before referral. The client receives the external contact details after transfer.

External resolution

Escalation if you remain dissatisfied

A dissatisfied client may use an external dispute-resolution route, including the DIFC Courts or an appropriate arbitration forum, and may contact the DFSA.

  • Submit a complaint electronically through the DFSA complaints service.
  • Telephone contact listed in the published procedure: +971 4 837 0200.
  • Write to DFSA Complaints, Level 13, The Gate, PO Box 75850, Dubai, UAE.
  • Visit the DFSA at Level 13, West Wing, DIFC.
Record keeping

Complaint records and trend review

Complaint communications are documented and retained, and complaint data is reviewed for trends and potential legal or operational risks.

Contact Compliance

Compliance Officer

Compliance can be contacted directly for further information or to raise a complaint.

Hexagone Group

Looking for the general complaint procedure?

For general complaints or where the relevant Hexagone company is not known, use the international Hexagone Group complaint-handling route.

View general Complaint Handling Procedure →

Customer complaint form

Submit a complaint online

Use the dedicated complaint report to provide the information contained in the approved form. Complaint submissions are kept separate from general enquiries and marketing flows.

Client Support

Submit a Complaint

A dedicated complaint-report route for complaints concerning Hexagone Capital (UAE) Limited. This form is separate from the website's general enquiry and sales journeys.

Customer Complaint Report

Online complaint report

The field structure below follows the approved Customer Complaint Report supplied for this website build. The investigation, resolution, action and approval fields are retained in the same sequence but are reserved for Hexagone Capital (UAE) Limited's internal Compliance process.

No additional regulated complaint fields have been invented for this prototype. Production submission routing must securely deliver complaint data to Compliance and must not add complainants to marketing or CRM promotion flows.
Complaint Record Source form header
Details of Complaint Information recorded at receipt
How the Complaint Was Received
Describe the subject matter with enough detail for Compliance to understand the concern. Do not enter passwords or account credentials.
Investigation and Resolution For Compliance use after receipt

These fields are included in the approved report and are completed internally by Compliance after the complaint is received.

Resolution Outcome
Action Taken to Resolve the Complaint For Compliance use after receipt
Action Taken to Resolve the Complaint Continuation field in the approved report
Approvals and Sign-Offs For Compliance use after receipt
Prepared by
Approved by

Complaint information may contain personal or sensitive information. Review the Privacy Policy. Complaint handling is separate from marketing consent and this form does not include newsletter or promotional opt-ins.

VIEW COMPLAINT HANDLING PROCEDURE

Prototype only: this standalone HTML demonstrates the complaint workflow and does not transmit information to a production Compliance backend.

Review your complaint

Check the information below before submitting. You can return to the complaint details if anything needs to be amended.

Complaint details

How the Complaint Was Received
Relevant Employees
Relevant Systems
Subject Matter

Compliance processing

Investigation, resolution, action-taken and approval fields are completed internally by Compliance after receipt and are therefore not part of your review.

Complaint received

Complaint Received

Your complaint has been submitted successfully in this prototype workflow. The intended production experience is for the Compliance team to review the information provided and follow the Complaint Handling Procedure.

For urgent queries, contact compliance@hexagone-capital.com or +971 4 837 0200.

Prototype state only - no data is transmitted by this standalone HTML file.

Hexagone Capital (UAE) LimitedRegistered with the Dubai International Financial Centre (DIFC)
Regulated by the DFSA, Licence Number: #F007596
Offline option

Customer Complaint Report

If you prefer to complete the approved report offline, use the downloadable PDF below and return it to Compliance.

Download Customer Complaint Report (PDF) →

Enquiry received

Thank you.

Your enquiry has been received. A member of the Hexagone Group team will review the information provided and respond through the contact details you submitted.

Return to Home→
Careers

Application received.

Thank you for your interest in Hexagone Group. The recruitment team will review your application and contact you if your profile is selected for the next stage.

View Careers→
404

The page could not be found.

The address may have changed, or the page may no longer be available. Use the links below to continue.

Return to Home→